Tag: Personal Finance

  • Your Student Loan Payment Could Jump From $0 to $900 Overnight — Here’s Your Real Deadline

    Your Student Loan Payment Could Jump From $0 to $900 Overnight — Here’s Your Real Deadline

    Are you one of the 7 million people on the SAVE student loan plan? If so, you need to read this before your next mailbox check.

    For a while now, SAVE borrowers have paid $0 a month. No payments, while a court fight over the plan played out.

    Why is my student loan payment $0 in the first place? For millions of borrowers, it comes down to one program: the SAVE plan. SAVE was tied up in court for years, and while the legal fight dragged on, payments for nearly 7 million borrowers were paused completely, some for over a year without owing a single dollar.

    That pause is ending now. SAVE was eliminated, and servicers are sending 90-day notices moving borrowers onto new repayment plans with real monthly bills attached. If your payment has been $0, don’t assume it stays that way. Log into your loan servicer’s portal and check your new plan and due date before the switch catches you off guard.

    That pause is ending. And most people don’t know their personal deadline yet.

    I didn’t realize how dangerous the silence was until I talked to someone getting their notice. They’d gotten used to $0 payments and hadn’t looked at their loan once in two years. Now they’re facing $850/month with no warning.
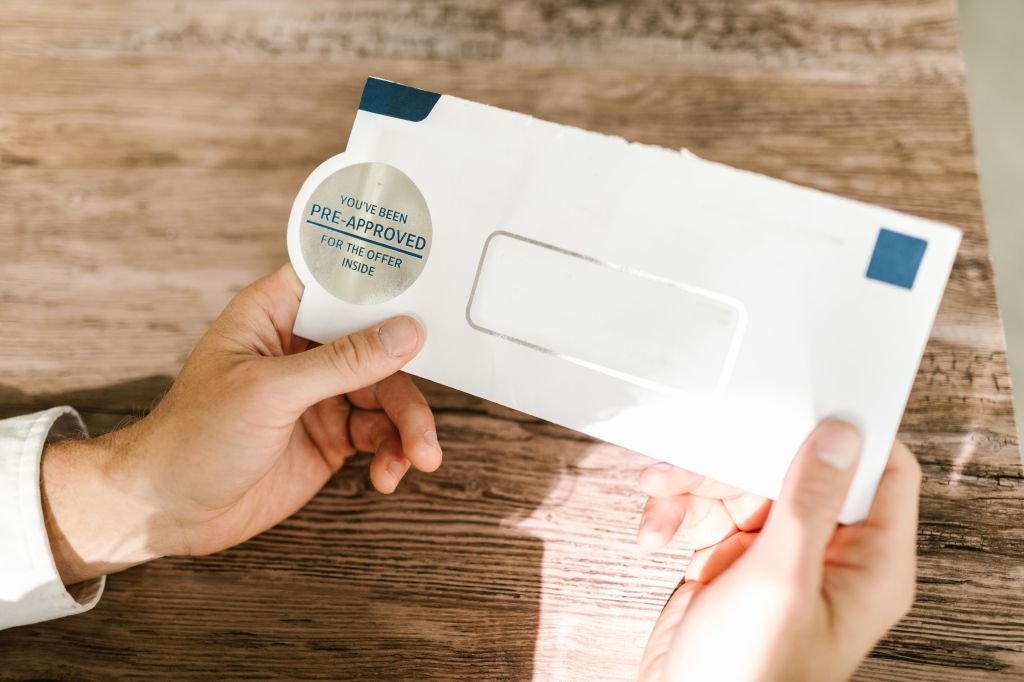
    Person opening an envelope containing a student loan billing statement

    Starting July 1, 2026, your loan servicer is sending out 90-day notices. The longest-enrolled borrowers are getting theirs first. Your own deadline is 90 days from the day YOU get your notice, not one single date for everyone.

    Here’s the part that should really get your attention. If you do nothing before your deadline, you get automatically moved into the Standard Repayment Plan. That plan is based on how much you owe, not how much you earn.

    For a lot of people, that means their payment jumps from $0 straight to $900 a month or more. Overnight. No warning beyond that one notice.

    Do you know your loan balance well enough to guess what your new payment could be?

    The scariest part isn’t even the money — it’s that the government decided your payment without asking if you could actually afford it. They just moved you into Standard and that was that.
    Person using a calculator while reviewing bills at a desk

    There’s a second, quieter problem too. If you’re working toward loan forgiveness, through Public Service Loan Forgiveness or an income-driven plan, every month you spent on this $0 forbearance did NOT count toward your forgiveness total. It felt free. It wasn’t really free — it was a pause on your progress too.

    This matters: My Student Loan Payment Just Changed and Nobody Warned Me

    Repayment PlanCurrent PaymentAfter July 1Forgiveness ProgressBest For
    SAVE (Before)$0EndingNo progress countingLimited time
    Standard RepaymentN/A$900+/monthCounts10-year plan
    Repayment Assistance PlanN/ALowerCountsLower income
    Tiered Standard PlanN/AVariesCountsMixed income
    PSLF Track$0ChangesCritical to actPublic service jobs

    So if forgiveness is part of your plan, waiting any longer costs you real time you can’t get back.

    Connect the dots: Medical Debt Can Still Wreck Your Credit Score
    Person checking a student loan account on a laptop at home

    Here’s what you can actually do right now, today. Log into studentaid.gov and check your servicer account for your exact deadline date. Use the official loan simulator tool to compare your real options, including the two new plans that started July 1: the Repayment Assistance Plan and the Tiered Standard Plan. If you’re chasing forgiveness, don’t wait for your deadline notice, switch as soon as you can.

    Are you on the SAVE plan right now? Do you already know your deadline, or are you still waiting on that notice?

    Disclaimer: This article is for educational purposes only and should not be considered as legal or financial advice. Student loan rules, plans, and deadlines vary by situation. Consult with a qualified financial advisor or your loan servicer before making student loan decisions.
  • Your Health Insurance Bill Just Jumped 58% — Here’s What Actually Happened

    Your Health Insurance Bill Just Jumped 58% — Here’s What Actually Happened

    Did your ACA marketplace health insurance bill go up this year? You’re not imagining it.

    The average person on marketplace insurance is now paying $178 a month, up from $113 last year. That’s a 58% jump, and it happened because of one thing: extra subsidies that started during COVID finally ran out at the end of 2025.

    Person reviewing a stack of medical bills at a kitchen table

    Those extra subsidies used to cap what you paid for insurance at 8.5% of your income, no matter how much you earned. Now that cap is gone for higher earners, and the discount is smaller for everyone else too.

    Some people got hit a lot harder than others. If you’re a 60-year-old couple making $85,000 a year, your yearly cost could be up over $22,000. If you’re a single person making $28,000, you’re looking at roughly $1,238 more a year — and your share of income going to insurance jumped from about 1% to almost 6%.

    I didn’t realize those COVID subsidies were temporary until I got my renewal notice. It felt like the government gave with one hand and took back with the other. Suddenly my insurance doubled.

    Income LevelAge2025 Monthly Cost2026 Monthly CostAnnual IncreaseImpact
    $28,000/yearSingle~$104$242+$1,6566% of income
    $85,000/year60-year-old couple~$1,833$1,833++VariesMay exceed $22K
    $50,000/year35-year-old~$144$250+$1,2723% of income
    Bronze PlanAll ages$100$120+$240High deductible

    Money isn’t the only thing that changed. Deductibles — the amount you pay out of pocket before insurance kicks in — hit a record $3,786 this year, up 37%. A lot of people responded by switching to cheaper “bronze” plans with lower monthly costs but much higher deductibles. That’s a real trade-off: less out of your paycheck now, more risk if you actually get sick.

    Deep dive: Medical Debt Can Still Wreck Your Credit Score

    Close-up of a health insurance enrollment form being filled out

    And here’s the part that worries me most: about 4.8 million people just stopped having marketplace coverage altogether. Some couldn’t afford the new price. Some just gave up and decided to go without. Nearly half of everyone who left was between 18 and 34 — young, usually healthier, people who often think they can go without insurance until something goes wrong.

    If you’re one of the people paying more right now, you’re not alone, and you’re not doing anything wrong. This wasn’t a personal budgeting mistake. It was a policy decision made in Washington, and it landed on real people’s bank accounts.

    This isn’t about cutting back on lattes or skipping dinner out. This is structural. People making $50K a year watching 3% of their entire income go to insurance — that’s not a personal finance problem, that’s a system problem.

    Related read: Your Paycheck Isn’t Keeping Up With Inflation (And That’s Not Your Fault)

    Family sitting together reviewing a household budget

    So what can you actually do about it? A few real options: check if you qualify for a cheaper bronze or catastrophic plan if you’re generally healthy and just need protection from a worst-case bill. Check if your state runs its own marketplace with extra state-level subsidies (some states added their own money to soften this). And if your income dropped or changed this year, report it — your subsidy is based on estimated income, and a correction could lower your bill.

    Did your premium go up this year? Did you switch plans, or did you drop coverage? I’d really like to know how this hit your own numbers.

    Disclaimer: This article is for educational purposes only and should not be considered as medical or health insurance advice. Insurance plans, subsidies, and coverage vary by state and individual circumstances. Consult with a qualified insurance agent or healthcare professional before making insurance decisions.

  • Only 6% of Workers Actually Qualify for the New “No Tax on Overtime” Law

    Only 6% of Workers Actually Qualify for the New “No Tax on Overtime” Law

    You’ve probably seen the headlines. Overtime pay is “tax-free” now. Sounds like a win for every hard-working American.

    Here’s the truth almost nobody is saying out loud: over 90% of American workers get zero benefit from this law. Not less benefit. Zero.

    When I saw the headline, I got excited for a second. Then I checked my job type and realized it didn’t apply to me. The headlines made it sound like everyone got this. They didn’t mention the 90% part.

    An office worker at a desk, representing salaried employees who don

    Picture two people. Maria works at a warehouse and gets paid extra when she works past 40 hours a week. James is salaried at an office job — he never gets “overtime pay,” no matter how late he stays.

    Maria might qualify for this new tax break. James never will. He was never eligible, law or no law.

    That split matters more than you’d think. Only about 6% of workers regularly get the kind of overtime that counts here. Most people are more like James than Maria.

    So before you get excited about this law, ask yourself the real question first: are you a Maria, or a James?

    Worth knowing: Tips Might Be Tax-Free Now. Here’s What I Learned

    Worker TypeFederal Overtime EligibleTax Deduction BenefitAnnual SavingsQualifies
    Hourly Warehouse Worker (Maria)YesOn overtime pay bonus$1,440Yes
    Salaried Office Worker (James)NoNone$0No
    State/Union OvertimeNoNot covered$0No
    Self-EmployedNoNot applicable$0No
    US Workers Affected6%~$130 avg

    And even if you’re a Maria, the benefit is smaller than it sounds. You don’t get to deduct your whole overtime paycheck. You only deduct the extra “half” — the bonus part of “time and a half” pay. Not the whole thing.

    A paycheck next to a calculator, representing how the overtime tax deduction is actually calculated

    Here’s what that means in real money. Averaged across every single tax filer in America — qualifying or not — this law saves people just $130 a year.

    For most of us, $130 is nice but it won’t change anything. For the actual Maria’s who work overtime regularly, it’s real money. But that’s such a small group that the average becomes almost meaningless.

    But for someone who really does qualify, like Maria, the number is better: about $1,440 back. That’s real money, if you’re one of the few this was built for.

    There’s one more catch. This money doesn’t show up in your paycheck this week. Your employer isn’t taking out less tax right now because of this law.

    You claim it when you file your taxes. So it shows up as a bigger refund next year — not as extra cash today.

    "A calendar marking tax season, representing when the overtime deduction actually pays out

    So ask yourself: does your overtime come from federal rules? Or from your state, or a union contract? Because this law doesn’t cover those.

    It’s worth checking before you count on money the headlines promised you — because for 9 out of 10 workers, that money was never coming.

    Also check: Your Paycheck Isn’t Keeping Up With Inflation (And That’s Not Your Fault)

    Disclaimer: This article is for educational purposes only and should not be considered as tax advice. Tax laws change frequently and eligibility varies. Consult with a qualified tax professional, CPA, or accountant before making tax-related decisions.

  • Average American Owes $6,715 in Credit Card Debt. The Fed Just Made That Number More Painful.

    Average American Owes $6,715 in Credit Card Debt. The Fed Just Made That Number More Painful.

    Person looking stressed while holding a credit card and looking at bills

    $6,715. That’s what the average American owes on credit cards right now, according to new data. It’s a record high, and it’s still climbing.

    Here’s the part most people miss. The Federal Reserve just met in June 2026. They decided to leave interest rates exactly where they were. No cut.

    That decision didn’t make headlines for long. But if you’re one of the millions carrying a balance, it hit your wallet directly.

    Why? Credit card interest is tied to the Fed’s rate. When the Fed holds steady instead of cutting, your card’s interest rate stays high too.

    Right now, the Fed’s own number for average credit card interest is 21.5%.

    Some reports that include lower-credit-score borrowers put the average even higher, near 25%. If your credit score isn’t great, you could be paying closer to 26%.

    Do the math on that $6,715 average balance at 21.5% interest.

    If you only pay the minimum, most of your payment doesn’t touch what you owe. It just covers interest. You could pay for years and barely move the number.

    Similar story: Buy Now, Pay Later Looked Smart. Here’s Why It’s Becoming a Debt Problem

    Debt OptionInterest RateMonthly PaymentYears to RepayTotal InterestNotes
    Credit Card (minimum)21.5%$1347+ years$4,500+Interest eats most payment
    Credit Card (aggressive)21.5%$3002.5 years$1,600Requires discipline
    Personal Loan9-12%$180-22036 months$1,200-1,400Fixed rate, predictable
    Balance Transfer (0% intro)0% (then 20%)$2252.5 years$500-600Works if paid before APR kicks in

    Have you ever actually checked your statement to see how much of your payment goes to interest versus your real balance? Most people never look. It’s not a fun number to see.

    When I finally checked mine, I was shocked. I’d been paying for three months and the balance barely moved. That’s when I realized I wasn’t actually paying off debt — I was just feeding interest.

    Calculator and bills on a kitchen table representing budgeting and debt

    Here’s the part that should really get your attention. Experts are now saying there’s a real chance the Fed raises rates again later in 2026, not lowers them.

    Related: Your Income Doesn’t Affect Your Credit Score. Here’s What Actually Does

    That means this could get more expensive before it gets cheaper.

    I remember thinking if rates go higher, my minimum payment stays the same but even less of it touches what I owe. It’s like running on a treadmill that keeps speeding up.

    Debt doesn’t wait for a “better time” to deal with it. It compounds every single day, whether you’re ready or not.

    Person sitting at a laptop reviewing their bank and credit card statements

    So what can someone actually do? A few real options: pay more than the minimum every month, even a little extra makes a difference over time. Look into a lower-interest personal loan to pay off the card faster. Talk to a nonprofit credit counselor — many offer free help and won’t push you toward anything. For people in serious trouble, formal debt relief exists too, though it can take years and hurts your credit short-term.

    If BNPL is part of what you’re dealing with, start with the free tracker first. It lays out every payment you owe across every app, in one place.

    If BNPL Apps Are Part of the Picture Too

    Credit card debt often isn’t the only balance stacking up. A lot of people carrying card debt are also juggling two or three BNPL apps at the same time, and those payments hit the same bank account on different days.

    The BNPL Stack Tracker is a simple fillable PDF that puts every BNPL payment in one place, so at least that part of the picture stays visible while you tackle the card balance. Check it out here — $9, instant download.

    None of these fix it overnight. But staying quiet while rates stay this high is the most expensive choice of all.

    If you’re carrying credit card debt right now, what’s stopping you from making one move on it today instead of “eventually”?

    Check this too: Medical Debt Can Still Wreck Your Credit Score

    Disclaimer: This article is for educational purposes only and should not be considered as financial advice. Debt solutions vary greatly based on individual circumstances. Consult with a qualified financial advisor, nonprofit credit counselor, or attorney before making debt management decisions.

  • Parents Are Spending Almost $500 Per Kid This Year. Here’s Why It Jumped So Fast.

    Parents Are Spending Almost $500 Per Kid This Year. Here’s Why It Jumped So Fast.

    Backpack and school supplies laid out for back-to-school shopping

    Back-to-school shopping used to just sting a little.

    This year it’s hitting different.

    I watched parents in stores this week doing something different — checking prices on phones, comparing across three stores before buying. Nobody was doing that last year.

    Parents across the US are now spending an average of $489 per child on school supplies, clothes, and shoes. That’s up from $437 last year.

    That’s not a small bump. That’s an 11.7% jump in one year.

    Regular inflation right now is only around 4%. So something else is pushing these prices up faster.

    Have you noticed prices climbing faster than usual lately, even outside of school shopping?

    Here’s what’s really going on.

    A lot of it comes down to tariffs — taxes on goods brought in from other countries. Average tariff rates right now sit at 10-13%. That’s the highest they’ve been since the 1940s.

    When I realized tariffs were the culprit, it stopped being about “I’m bad at budgeting” and became about something completely out of my control. That’s a different kind of frustrating.

    Clothes, shoes, and electronics are some of the categories getting hit the hardest. And a lot of school supplies fall right into those categories.

    Parent and child shopping together for back-to-school items

    One estimate from the Tax Foundation says tariffs alone are adding about $700 in extra cost per household this year. That’s real money. That’s a car payment. That’s a month of groceries for some families.

    And it’s not hitting everyone the same way.

    Middle-income families — households making between $50,000 and $150,000 a year — saw their budgets jump the most. About 20% higher than last year, up to $495 per child.

    Higher-income families are still spending more overall. But the percentage jump was smaller for them.

    Lower-income families grew their spending the least — under 4%. Not because things got cheaper for them. Because they simply don’t have room to spend more, even when prices go up.

    Does that sound familiar? Cutting corners not because you want to, but because there’s no other option?

    Read also: Gas Prices Are Destroying My Budget

    Income LevelAnnual Household Income2025 Per-Kid Cost2026 Per-Kid Cost% IncreaseImpact
    Lower Income$30K-50K$450$4684%Least impact
    Middle Income$50K-150K$437$49511.7%Hardest hit
    Upper Income$150K+$600+$650+~8%Most dollars, smaller %
    Average$437$48911.7%National average

    : Don’t miss: I Cut My Coffee, Dessert, and DoorDash

    So what are families actually doing about it?

    A lot of them are shopping earlier than usual, trying to catch sales before prices climb further. Others are comparing prices more carefully, checking discount stores, or buying fewer “extra” items and sticking to just what’s needed.

    None of it fixes the real problem. It just softens it a little.

    Parent reviewing a shopping receipt, looking concerned about rising prices

    If you’re a parent dealing with this right now, you’re not imagining it. Prices really did jump faster than normal this year. And it’s not just you being bad with money — it’s the actual numbers moving against you.

    What would you cut first if your own budget got squeezed by 11% overnight?

    Worth checking: Your Paycheck Isn’t Keeping Up With Inflation

    Disclaimer: This article is for educational purposes only and should not be considered as financial advice. Tariff impacts, pricing, and cost data are subject to change. Consult with a financial advisor before making major purchasing or budgeting decisions.

  • I Cut My Coffee, My Dessert, and My DoorDash. My Bank Account Still Didn’t Move.

    I Cut My Coffee, My Dessert, and My DoorDash. My Bank Account Still Didn’t Move.

     a coffee cup next to a receipt

    Three months ago I got serious. Really serious.

    No more $8 coffee on the way to work. No dessert when we ate out. No more DoorDash on the nights I was too tired to cook.

    I shopped for groceries exactly once a week, no extra trips, no impulse buys. I even downgraded my gym membership.

    I did everything the money-saving videos online told me to do.

    And you know what? My checking account still looked almost the same at the end of the month.

    Have you ever done everything “right” with money and still felt like nothing changed? That’s exactly where I was.

    The internet is obsessed with this right now

    Right now there’s a huge debate online about saving money. I mean a huge one.

    One side is all in on extreme budgeting. Skip the coffee. Skip the dessert. Cook every single meal. Track every dollar in an app. One person online said they saved $30,000 in a year just from cutting small daily spending.

    Thirty thousand dollars. From coffee and takeout. That number stopped me too.

    The other side pushed back hard. And honestly, their point hit me harder than the $30,000 story did.

     someone checking a bank app on their phone, looking a little worried

    The comment that stopped me cold

    Someone wrote this under one of those videos: “You can’t budget your way out of poverty. The solution, sadly, is to increase your income.”

    Another person added: “Budgeting is important. But we can’t budget ourselves to death.”

    I read that twice. Then I sat with it for a long time.

    Because here’s the thing nobody talks about. If your paycheck barely covers rent, groceries, and gas — there is no amount of skipped coffee that fixes that. You can only cut so much fat before you start cutting into bone.

    So who’s right?

    Honestly? I think both sides are a little bit right, and a little bit wrong.

    Cutting small stuff does help. I’m not broke because of coffee. Three months of small cuts did put a little extra in my account — not nothing, but not life-changing either.

    But budgeting alone didn’t fix the real problem. The real problem was that my income wasn’t growing while my bills kept getting bigger.

    Budgeting is a tool. It’s not a rescue plan. It can help you stop leaking money — but it can’t create money that isn’t there in the first place.

    Strategy3-Month Impact12-Month ProjectionReality Check
    Cut coffee ($8/day)+$720 saved+$2,880/yearHelpful but limited
    Cut DoorDash (2x/week)+$400 saved+$1,600/yearHelpful but limited
    Total Cutting Only+$1,120+$4,480/yearDoesn’t fix core problem
    Add $100 freelance/month+$300 earned+$1,200/yearIncome growth works
    Cutting + Extra Income Combined+$1,420+$5,680/yearBoth matter together

    Related: Is Your Side Hustle Working, or Are You Just Tired?

    What actually helped me more than cutting coffee

    Once I stopped only cutting and started also looking for small ways to earn — even $50 or $100 extra a month — that’s when I actually felt something shift.

    It didn’t have to be a whole new career. A few extra hours of freelance work. Selling stuff I wasn’t using. Asking about a raise I’d been too nervous to ask for.

    None of it was huge on its own. But it moved the needle in a way that skipping dessert never did.

     a simple handwritten budget list on a notebook

    My honest take

    Cut what you can, sure. Don’t waste money on things that don’t matter to you.

    But don’t beat yourself up if cutting alone isn’t enough. That’s not a personal failure. For a lot of us, it’s just math — the numbers don’t work no matter how careful you are.

    So here’s my real question for you: have you ever cut everything you could and still felt stuck? What actually moved the needle for you — cutting spending, or finding a way to earn a little more?

    Tell me in the comments. I really want to know I’m not the only one.

    You might also like: 5 Simple Ways to Save $100 This Month

    Disclaimer: This article is for educational purposes only and should not be considered as financial advice. Personal financial situations vary greatly. Consult with a qualified financial advisor before making major financial decisions.

  • You’re Allowed to Save an Extra $7,500 a Year for Retirement. Almost Nobody Does It.

    You’re Allowed to Save an Extra $7,500 a Year for Retirement. Almost Nobody Does It.

    couple reviewing retirement savings plan

    Here’s something most people don’t know.

    If you’re over 50 in America, the government lets you save extra money for retirement. On top of the normal limit.

    It’s called a “catch-up contribution.” Up to $7,500 more a year, tax-advantaged, just for being 50 or older.

    Sounds like free help, right? A real chance to catch up if you started saving late.

    Here’s the part that’s hard to believe. The average person who qualifies adds exactly $0 of it.

    Not a small amount. Zero.

    Think about what that really means. Millions of people are eligible for extra help. And almost nobody uses it.

    Why would that happen? There are a few real reasons, and none of them make people careless or lazy.

    Some people don’t know the option exists. Nobody told them, so they never looked for it. You can’t use a door you don’t know is there.

    Some people know about it, but there’s simply no extra money left at the end of the month to add. Life costs what it costs.

    And some people feel behind on retirement savings already. So an extra rule about extra savings feels like one more thing to worry about, not helpful. It feels easier to not think about it at all.

    Here’s the honest truth, though. A rule you don’t know about can’t help you. Not knowing doesn’t protect you from falling behind. It just delays finding out.

    man calculator finance desk

    You don’t have to use all $7,500. Nobody said all or nothing.

    You don’t have to use any specific amount. Even a small amount counts.

    But you can’t decide “not right now” if you didn’t even know it was an option in the first place. That’s not a choice. That’s just missing information.

    If you’re over 50 and saving for retirement, this is worth 10 minutes of your time. Just 10 minutes. Ask your plan provider two simple questions.

    Am I eligible for catch-up contributions? And how much am I currently putting toward that limit?

    Most people, when they finally check, are surprised by the answer. Usually not in a good way.

    But here’s the useful part. Once you know the real number, you can actually do something about it. You can’t fix what you don’t measure.

    Small amounts add up more than people expect. Even $100 a month extra, over 10 years, is real money working for you instead of sitting unused in a “someday” pile.

    Contribution TypeAnnual Limit (2026)Age EligibilityTax Advantage10-Year Growth
    Standard 401(k)$23,500AllTax-deferred+10 years × $23,500
    Catch-up 401(k)$7,500 extra50+Tax-deferred+$750,000
    Combined (50+)$31,00050+Tax-deferred+$31,000/year
    No contribution$0N/ANone$0

    Learn more: You Might Already Have Enough Money to Retire

    Compare that to doing nothing. Zero dollars added always grows into exactly zero dollars later. That part is guaranteed.

    The system built a door for people who started saving late. A second chance, built right into the rules.

    Most people just don’t know it’s there. And a second chance nobody uses might as well not exist.

    So consider this your nudge. Not to panic. Just to check.

    Did you know about catch-up contributions before reading this? Are you using yours, or is this brand new information for you? Tell me in the comments — I want to know how many of us are finding this out for the first time.

    See also: Your Savings Account Might Be Secretly Costing You Money

    Disclaimer: This article is for educational purposes only and should not be considered as financial or retirement advice. Tax laws and contribution limits change frequently. Consult with a qualified tax professional, accountant, and retirement planning advisor before making retirement savings decisions.

  • You Might Already Have Enough Money to Retire. So Why Are You Still Working?

    You Might Already Have Enough Money to Retire. So Why Are You Still Working?

    older worker sitting at desk thinking about retirement

    Do you know someone who keeps saying “just one more year” before they retire?

    Then one more year turns into two. Then three. Then they’re still saying it five years later.

    This has a name now. Financial experts call it “one more year syndrome.”

    It happens to people who already have enough money saved. Enough to stop working. Enough to be truly okay.

    But they don’t stop. They keep showing up to a job they don’t need anymore.

    Why? It’s not really about the money. It’s about fear.

    What if the market crashes right after I retire? What if I need more than I think? What if I’m bored? What if something goes wrong and I can’t fix it because I’m not earning anymore?

    So they stay. One more year. Then another. Then another.

    Here’s the hard truth nobody tells you. Some of these people work five, six, even ten extra years they never actually needed to work.

    Years DelayedIncome EarnedTime Lost with FamilyOpportunity CostRegret Factor
    Retire on scheduleStopSpent with loved onesExperiences livedNone
    “One more year” (×5)+5 years salary5 years missedGrandkids grew upHigh
    “One more year” (×10)+10 years salary10 years missedMajor life eventsVery High

    Learn more: You’re Allowed to Save an Extra $7,500 for Retirement

    Think about what that costs. Not in dollars. In mornings.

    Five years of mornings they could have spent with their grandkids. Five years of trips never taken because “next year is safer.” Five years of their own parents getting older while they stayed at a desk instead of visiting.

    Money missing from your bank account, you can always earn more of. Time missing from your life, you can never get back. That’s the part that makes this syndrome so dangerous.

    senior couple looking at retirement savings papers

    So how do you know if you’re in it?

    Ask yourself these questions honestly:

    Do I have a real number — an actual number, not a feeling — that tells me I’m ready? Or am I just guessing?

    If my accountant told me tomorrow “you have enough,” would I actually stop? Or would I find a new reason to stay?

    Am I staying because I love the work? Or because stopping feels scary?

    There’s a difference between those two answers. One means you’re choosing your job. The other means fear is choosing it for you.

    A good financial advisor can run your real numbers. Not guesses. Not “I think I’ll be fine.” Real numbers, based on what you actually have and actually spend.

    Sometimes those numbers say you’re already there. You just haven’t let yourself believe it yet.

    And here’s the thing — even people who aren’t near retirement age can learn from this. The same fear that keeps a 65-year-old at a desk is the same fear that keeps a lot of us stuck in comfortable-but-wrong situations. Waiting for a “safer” moment that never actually comes.

    Maybe the real lesson isn’t only about retirement. Maybe it’s about noticing when fear is running your decisions instead of facts.

    Have you or someone you know ever felt stuck in “one more year”? What finally made them stop — or are they still stuck? Tell me in the comments, I really want to hear your story.

    See also: Your Income Doesn’t Affect Your Credit Score

    Disclaimer: This article is for educational purposes only and should not be considered as financial or retirement advice. Retirement decisions are highly personal and vary based on individual circumstances. Consult with a qualified financial advisor, accountant, and retirement planning professional before making retirement decisions.

  • Your Savings Account Might Be Secretly Costing You Money

    Your Savings Account Might Be Secretly Costing You Money

    Person checking high-yield savings account interest rate on a mobile banking app

    Quick question. Do you know what interest rate your savings account pays you right now, today?

    Most people have no idea. And that gap in knowledge is quietly costing them real money, every single month.

    Here’s a number that might surprise you. The average savings account across the US pays only about 0.38% interest, according to FDIC data from mid-June 2026. That’s almost nothing.

    Some of the biggest banks in the country — the kind everyone’s heard of — pay as little as 0.01% on regular savings accounts.

    Let’s make that real with actual math. Put $1,000 in an account paying 0.01%, and after a full year, you’ve earned exactly 10 cents. Ten cents. Less than a piece of candy.

    Now here’s the other side of the same coin. As of early July 2026, some high-yield savings accounts are paying up to 5.00% APY — and putting that same $1,000 in a 4% account earns you $40 in a year instead of 10 cents.

    Person checking high-yield savings account interest rate on a mobile banking app

    Same $1,000. Same safety. Same government protection on your deposit. One bank gives you 10 cents. Another gives you $40. Nothing else about your money changed — only where you kept it.

    Account TypeInterest Rate (July 2026)Annual Interest on $1,000FDIC ProtectedAccessibility
    Traditional Bank (0.01%)0.01%$0.10YesEasy
    Average Savings Account (0.38%)0.38%$3.80YesEasy
    High-Yield Savings (4%)4.00%$40YesOnline
    High-Yield Savings (5%)5.00%$50YesOnline
    Annual Difference$49.90 more

    Learn more: Your Bank Account Fees Are Eating My Paycheck

    Why does this happen? It’s simple, and a little bit sneaky. Big traditional banks know most people never bother switching accounts. Once you’re in, you tend to stay, even when it costs you.

    Online banks work differently. They don’t pay for branch buildings or tellers, so they pass those savings to you as higher interest instead. That’s the whole trick. Lower overhead, higher rate.

    Here’s what surprises people most. Switching doesn’t mean closing your checking account or leaving your bank completely. You keep your checking account exactly where it is. You simply open a separate savings account somewhere else, and move your extra cash — money you’re not spending this week — into that account instead.

    A high-yield savings account still keeps your money insured up to $250,000 by the FDIC, the same protection a regular savings account has. You’re not taking on extra risk. You’re just stopping the leak.

    Opening one usually takes about 15 minutes online. No finance degree. No paperwork mailed anywhere. No visit to a branch.

    So why doesn’t everyone already do this?

    Honestly? Because nobody tells them. Your bank isn’t going to mail you a letter that says “hey, you’re losing money every month — here’s a better option somewhere else.” That letter will never come.

    That silence is exactly why this kind of information matters. The people who know this, keep more of their own money. The people who don’t, keep losing it quietly, month after month, year after year, without ever noticing.

    Person opening a high-yield savings account online from home

    One honest note before you go check your own account: rates like these move. Because the Fed has cut rates before, banks can and do lower savings rates over time, so whatever number you see today, always double check the current rate before you move any money.

    Have you checked your savings account’s interest rate lately? What did you find out — good news, or a wake-up call?

    See also: You Might Already Have Enough Money to Retire

    Disclaimer: This article is for educational purposes only and should not be considered as financial advice. Interest rates change frequently and vary by bank and date. Always verify current rates with the financial institution before opening an account. Consult with a qualified financial advisor before making financial decisions.

  • A New $1,000 Account Just Opened for Millions of American Kids. Do You Know About It?

    A New $1,000 Account Just Opened for Millions of American Kids. Do You Know About It?

    Something big happened in American finance today.

    Starting July 4, millions of kids across the US just got access to a brand new kind of savings account.

    It’s called a Trump Account. And it comes with free government money attached.

    Have you heard of it yet? A lot of parents haven’t.

    Here’s the simple version. Eligible kids under 18 get a one-time $1,000 deposit from the federal government.

    That money goes into an investment account. It grows over time, in the stock market.

    Parents, grandparents, and other family members can add up to $5,000 more every year.

    Employers can chip in too. Up to $2,500 a year, if a company decides to offer it as a benefit.

    The money stays locked until the child turns 18. No withdrawals before that, no exceptions.

    Once the child turns 18, the account becomes a regular retirement account. It works a lot like a traditional IRA from there.

    Sounds simple, right? But here’s where it gets interesting.

    Some financial experts say these accounts could grow to over $200,000 by the time a kid turns 55 — if the market performs like it has in the past.

    That’s just from the free $1,000. No extra contributions needed.

    If a family adds the full $5,000 every year on top of that, some projections go as high as $13 million by retirement age.

    But other experts are more cautious. Nobody can promise the market will keep growing at the same pace it has before.

    Family Income LevelFree Government GiftAnnual Family AdditionsProjected Age 55Age 30 Estimate
    Lower Income ($30K/year)$1,000$0-500$50,000-75,000$2,500
    Middle Income ($60K/year)$1,000$2,500-3,000$400,000-600,000$25,000
    Upper Income ($120K+/year)$1,000$5,000/year$200,000-13M+$150,000

    Learn more: You Might Already Have Enough Money to Retire

    How do you actually sign up?

    Parents can enroll a child through a tax form called IRS Form 4547, filed with their tax return.

    Or you can go straight to TrumpAccounts.gov and sign up there directly.

    After that, there’s a Trump Accounts app you download to check on the account and manage it going forward.

    A scam warning worth knowing

    The government has already warned people about this. Official emails only come from one address: no-reply@trumpaccounts.treasury.gov.

    If anyone calls or texts you about a Trump Account, don’t respond. That’s not how the real program contacts you.

    Always type TrumpAccounts.gov into your browser yourself. Never click a link someone sends you.

    Now the bigger question underneath all of this.

    Wealthier families can afford to add the full $5,000 every single year.

    Lower-income families often can’t. So the gap between rich and poor families may not close. It may just get pushed 18 years down the road.

    One researcher estimated a wealthy family could build $150,000 for their child by age 30. A lower-income family might end up with closer to $2,500.

    Is a free $1,000 still worth taking? Most experts say yes — free money is free money.

    But is it a real fix for the wealth gap, or just a head start that favors people who are already ahead?

    If you’re a parent in the US, have you signed up your child yet? Or are you still deciding if it’s worth it?

    Tell me what you think in the comments below.

    See also: You’re Allowed to Save an Extra $7,500 for Retirement

    Disclaimer: This article is for educational purposes only and should not be considered as financial or investment advice. Market performance projections are hypothetical and not guaranteed. Consult with a qualified financial advisor before making investment decisions for your child.