Category: Uncategorized

  • You Might Not Get a 1099-K This Year — That Doesn’t Mean You’re Off the Hook

    You Might Not Get a 1099-K This Year — That Doesn’t Mean You’re Off the Hook

    Why didn’t I get a 1099-K this year? If you sold something online, drove for a rideshare app, or freelanced on the side in 2026, you might be asking yourself exactly that.

    For years, the rule everyone braced for was simple: earn more than $600 through PayPal, Venmo, Etsy, or similar platforms, and a 1099-K would show up in your inbox. That threshold never actually took effect. In July 2025, a new law reversed course completely, and most people never got the memo.
    Person looking confused while reviewing tax paperwork at a desk

    Here’s what actually changed. According to Fidelity’s breakdown of the new rules, the One Big Beautiful Bill Act restored the original 1099-K threshold: $20,000 in payments and more than 200 transactions in a year. That’s a massive jump from the $600 figure that had been widely reported and expected for 2026.

    This law reversal didn’t happen quietly either. Avalara’s analysis of the legislation confirms the Act fully repealed the lower $600 threshold that the American Rescue Plan Act had set back in 2021, restoring the pre-2021 rule instead of just delaying it again. This matters because a lot of side hustlers spent the last two years preparing for a form that was never going to show up at the lower threshold. Someone who sold $3,000 worth of items on Etsy or made $1,800 driving part-time this year likely won’t get a 1099-K at all under the current rule.
    Person packaging items for an online sale, representing side hustle or small business income

    Worth knowing: this isn’t the only recent shift affecting people earning extra money on the side.
    45% of Americans Have a Side Hustle Now. Here’s Why (And Whether You Need One Too).

    Here’s the part that trips people up. Not getting a 1099-K does not mean that income is tax-free. A guide from Tab Service Company on the 2026 rules puts it directly: thresholds determine when a platform has to file a form, not what income is actually taxable. Every dollar earned from a side hustle is still reportable, whether or not paperwork shows up confirming it.

    This distinction matters even more for the platforms the examples above don’t quite cover, like Facebook Marketplace, Poshmark, and Mercari, where most sellers are just clearing out a closet, not running a business. According to the IRS’s own guidance on Form 1099-K, selling a personal item for less than you originally paid for it isn’t taxable at all. You’re allowed to zero out that reported amount on Schedule 1 of your return instead of paying anything on it, since a form showing up doesn’t automatically mean a profit was made. A gain only shows up if you sold something for more than you originally paid, which is rare for used furniture, old electronics, or worn clothing.

    This same declutter-for-cash habit already saves a lot of people real money before taxes even enter the picture.
    60% of Americans Bought Secondhand Last Year, and 8 in 10 Say It’s About Money, Not the Planet. I’ve Been Doing This My Whole Life.

    There’s a second, separate change worth knowing about too. Forms 1099-NEC and 1099-MISC, the ones businesses use to report payments to contractors directly, had their own threshold raised from $600 to $2,000 starting this tax year. That’s a different form covering different situations, mainly freelance and contract work paid outside of apps like PayPal or Venmo.
     Person working as a freelancer on a laptop at a home office desk

    Not every state follows the federal threshold either. Some states set their own, lower reporting requirements for 1099-K regardless of what the federal rule says. A resident earning side income in one of those states could still receive a form even while the federal threshold sits at $20,000. Checking state-specific rules matters just as much as the federal number here.

    This is why keeping personal records matters more than waiting on paperwork.
    Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed.

    Some tax professionals see the higher threshold as reasonable relief for casual sellers and small earners who never should have needed a tax form for reselling used furniture or old electronics. Others point out that the swinging thresholds over the past several years, first dropping, now jumping back up, have made it genuinely hard for anyone to know what to expect year to year. Both points are fair. The practical result is the same regardless: fewer forms are being issued, but the underlying tax obligation hasn’t moved at all.

    Nobody enjoys tracking income by hand when a form was supposed to do it automatically. That extra step feels unnecessary right up until the year it turns out to matter.

    Since side income this year might come from three or four different apps at once, piecing it together from memory next April is the hard way to do it. A free tracker built for exactly this kind of running total takes less time to set up than digging through a year of Venmo notifications later.

    The simplest fix costs nothing and takes minutes a week. Keep a running log of side income as it comes in, whether that’s a notes app, a spreadsheet, or a notebook by the desk. Include the date, the source, and the amount. Come tax season, that log matters more than whichever forms happen to show up.

    Form TypePre-2025 Plan2026 Rule (Current)Who It Affects
    1099-K (PayPal, Venmo, Etsy, Cash App)$600, no transaction minimum$20,000 + 200 transactionsCasual sellers, gig workers, small resellers
    1099-NEC (direct contractor payments)$600$2,000Freelancers paid directly, not through apps
    1099-MISC (misc. business payments)$600$2,000Royalties, rents, other business payments
    State-level 1099-K rulesN/AVaries — some states below $20,000Residents of states with stricter local rules

    The rules changed twice in three years. The responsibility to report side income never did.

    Did you expect a 1099-K this year, and were you surprised by what actually applies to your situation?

    Disclaimer: This article is for general informational purposes only and does not constitute tax or legal advice. Tax rules vary by individual circumstances and state of residence. Consult a licensed tax professional for guidance specific to your situation.
  • How to Track Multiple Buy Now Pay Later Apps Without Losing Track of What You Owe

    How to Track Multiple Buy Now Pay Later Apps Without Losing Track of What You Owe

    Why is tracking Buy Now Pay Later payments so confusing? The answer is simple: each app runs on its own schedule, pulls from the same bank account, and has no idea the others exist.

    Klarna, Afterpay, Affirm, Zip, Sezzle — most BNPL users aren’t using just one. A typical shopper juggling three or four active plans at once has effectively taken on a second, invisible payment calendar that no single app shows them in full.

    Person looking at multiple finance apps on a phone, trying to track separate payments

    Here’s what makes this worse in 2026. According to CNBC Select’s review of the top BNPL providers, FICO started factoring BNPL loans into credit scores in late 2025. That means the payment tracking problem isn’t just about avoiding overdraft fees anymore. Missed or overlapping BNPL payments can now show up on a credit report the same way a missed credit card payment would.

    Most advice on this topic stops at “just be careful.” A guide from EarnIn on managing multiple BNPL plans puts it plainly: keep all active plans visible in one place, and avoid juggling multiple plans at once because overlapping payments can add up fast. That’s the right idea, but it doesn’t say how to actually see them all at once when each app only shows its own schedule.

    Calendar with payment due date reminders marked, representing BNPL payment tracking

    Three ways people actually try to solve this:

    1. Checking each app individually. This works until it doesn’t. The moment someone has three or four plans running, checking each app separately before every purchase or bill payment becomes its own task, and it’s the first thing people stop doing once life gets busy.

    2. A spreadsheet. More reliable than memory, but it requires building the structure yourself, remembering to update it after every purchase, and doing the math manually to check for overlapping due dates.

    3. A dedicated one-page tracker. This is the middle ground: less setup than a spreadsheet, more complete than checking apps one by one, and built specifically to catch the problem before it becomes a fee.

    Worth knowing: BNPL debt rarely feels like debt until multiple payments land the same week.
    Buy Now, Pay Later Looked Smart. Here’s Why It’s Becoming a Debt Problem for Millions.

    The core problem isn’t any single app. It’s that none of them talk to each other, and a bank account doesn’t care which app is pulling money on a given day, only that enough is there when it happens.

    Person writing payment details into a planner or tracking sheet by hand

    A simple fix that works regardless of which method someone picks: check every active BNPL plan on the same day each week, write down the app, the amount, and the next due date in one place, and add them up against the next 14 days of expected bank balance. That single number, one number, catches most collision problems before they become a fee.

    This is why a dedicated tracker helps more than a general budgeting app. Most budgeting apps are built to categorize spending after it happens. What actually prevents an overdraft is seeing what’s coming before it hits, specifically the next two weeks, specifically across every BNPL app at once.

    For anyone who wants a version of this already built rather than starting from a blank spreadsheet, the BNPL Stack Tracker is a $9 fillable PDF that does exactly this: one page for every open BNPL account, one page to catch 14-day payment collisions before they trigger a fee, and one page to decide which apps are actually worth keeping.

    MethodSetup TimeCatches Overlapping PaymentsOngoing Effort
    Checking each appNoneNoRepeated, easy to skip
    Spreadsheet20-30 minYes, if built correctlyManual updates each time
    Dedicated tracker5 minYes, built inWeekly check

    “Nobody sets out to lose track of four different payment schedules on purpose. It happens gradually, one convenient checkout button at a time, until the due dates stop lining up with the bank balance. That gap between what people think they owe and what’s actually scheduled to leave their account is where the real damage happens. It’s not a math problem until it suddenly is.

    How many BNPL apps do you currently have open, and could you name all of their next due dates right now without checking your phone?

    Disclaimer: This article is for general informational purposes only and does not constitute financial advice. BNPL terms, fees, and credit reporting practices vary by provider. Consult a licensed financial advisor for guidance specific to your situation.
  • 401(k) Balances Just Hit a Record High — So Did Emergency Withdrawals From Them

    401(k) Balances Just Hit a Record High — So Did Emergency Withdrawals From Them

    Something strange happened with American retirement accounts in 2025. Balances hit an all-time high. So did the number of people raiding those same accounts just to survive.

    Vanguard’s newest report found the average 401(k) balance climbed to $167,970 by the end of 2025, a record. At the same time, 6% of plan participants took a hardship withdrawal that same year, also a record, and triple the rate from before the pandemic.

    Those two numbers shouldn’t move together. One says people are saving more than ever. The other says a growing share of them can’t make it through a crisis without pulling from that same account.

    Person looking stressed while reviewing a retirement account balance statement

    Here’s what’s driving the gap. According to Yahoo Finance’s coverage of Vanguard’s How America Saves report, layoffs surged to their highest level since the pandemic in 2025, and credit card delinquencies hit a 13-year high. Rising retirement balances came mostly from strong stock market gains and automatic enrollment features, not from people having more spare cash to set aside. The savings and the desperation grew from two completely different sources.

    Most hardship withdrawals aren’t going toward anything optional. The IRS recognizes six approved reasons for a hardship withdrawal, and the top ones are medical bills, preventing eviction or foreclosure, and funeral costs. This isn’t a luxury purchase problem. It’s people using retirement money as a last resort because nothing else was left.

     Eviction or foreclosure notice paperwork laid out on a table

    Worth knowing: an emergency fund exists specifically to prevent this exact situation from happening to your retirement money.
    Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed.

    The real cost of a hardship withdrawal isn’t just the tax bill, though that part hurts too. A TheStreet analysis of the Vanguard data found that a 35-year-old who pulls out $10,000 today loses more than $76,000 in future growth by retirement age, assuming a standard 7% annual return. A 45-year-old taking a $20,000 withdrawal loses roughly $77,400 in potential growth over the shorter remaining timeline. Unlike a 401(k) loan, a hardship withdrawal can never be paid back into the account.

    Not every financial planner sees this trend as purely alarming. Some point out that the same report shows record numbers of employees enrolled in retirement plans, and stronger long-term investing behavior overall, with only 5% of participants making trades even during market volatility. The system is working as designed for a lot of people. It’s the growing minority pulling out early that’s the concerning half of the story.

    Financial advisor discussing retirement options with a client at a desk

    Think about: the earlier you build a real safety net outside your retirement account, the less likely you are to ever need to touch it early.
    You’re Allowed to Save an Extra $7,500 for Retirement. Most People Don’t.

    If you’re facing a real emergency and a hardship withdrawal feels like the only option, a few alternatives are worth checking first. A 401(k) loan lets you pay yourself back over time instead of losing the money permanently, though it comes with its own risks if you leave your job before repaying it. Some employers also offer emergency savings features built directly into the retirement plan now, specifically designed to prevent people from needing to touch their long-term savings at all.

    Nobody takes money out of their own retirement account because they want to. It’s usually the last option left standing after everything else has already been tried.

    Metric202020242025
    Hardship withdrawal rate2%5%6% (record)
    Average 401(k) balanceLowerRising$167,970 (record)
    Cost to a 35-year-old on $10K withdrawal~$76,000 in lost growth

    A record balance and a record withdrawal rate happening in the same year isn’t a contradiction. It’s a picture of an economy where some people are getting ahead, and others are barely holding on, using the same accounts to do both.

    Have you ever had to consider pulling money from a retirement account early, and what did you end up doing instead?

    Disclaimer: This article is for general informational purposes only and does not constitute financial or tax advice. Retirement account rules and tax consequences vary by individual circumstances. Consult a licensed financial advisor or tax professional for guidance specific to your situation.

  • How to Use Record-High Apartment Vacancies to Negotiate Your Rent Down in 2026

    How to Use Record-High Apartment Vacancies to Negotiate Your Rent Down in 2026

    Why does everyone assume rent only goes up? That assumption made sense for years. It doesn’t anymore, at least not everywhere, and most renters have no idea the numbers just shifted in their favor.

    Apartment vacancies hit a record 8.6% in early 2026, up from 7.2% just months earlier. That means landlords have more empty units sitting unrented than they’ve had in years, and empty units cost landlords money every single day they stay empty.

    I remember signing a lease years ago without asking a single question about the price, because it never occurred to me that the number on the page wasn’t final. Looking back, that assumption cost me more than it should have.

    Person reviewing a lease agreement while considering negotiating the rent price

    Here’s why this matters for you directly. When vacancy rates climb this high, according to CoStar Group’s 2026 Multifamily National Report, property managers often extend more concessions just to fill units. That includes waived fees, a free month of rent, or flexibility on the monthly price itself, especially in buildings that have sat vacant for weeks.

    This isn’t happening everywhere the same way. National rent growth slowed to just 0.4% year over year, way down from 1.5% the year before, but the picture changes city by city. Places like Chicago, Cincinnati, and Philadelphia are still seeing real increases, while other markets are flat or even falling. Checking your specific city’s vacancy trend, not just the national headline, tells you how much leverage you actually have.

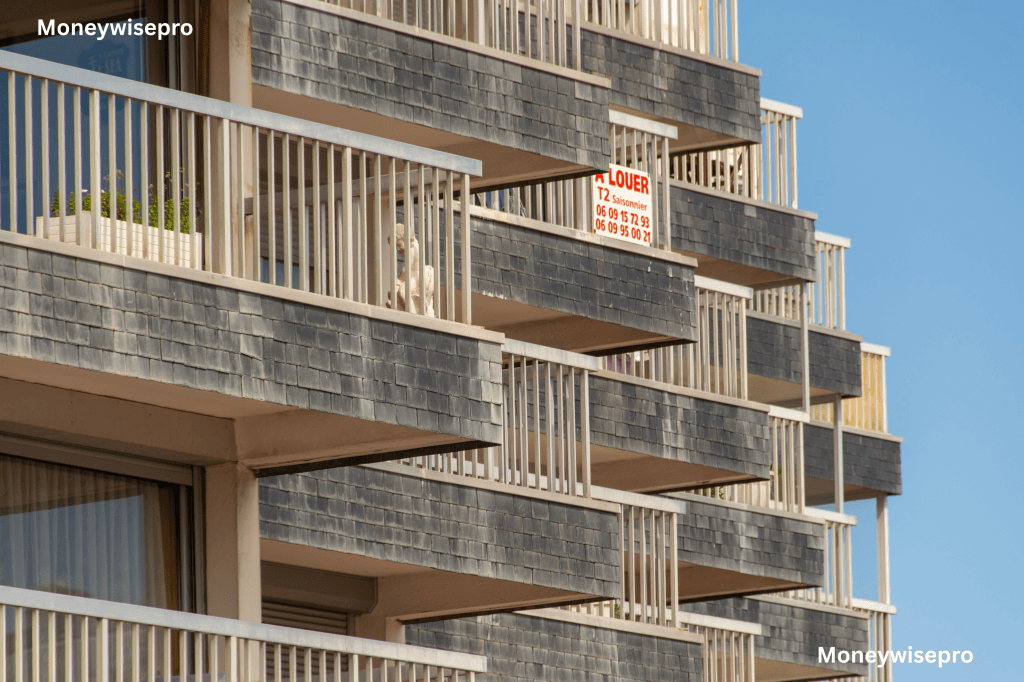
    Apartment building with a for rent sign, showing an empty unit available

    Worth knowing: rent isn’t the only monthly cost quietly climbing while your paycheck stays flat.
    Your Paycheck Isn’t Keeping Up With Inflation. Here’s Why.

    Not everyone agrees renters have real power right now. Some housing economists point out that the number of renters facing serious cost burdens just hit a record high too, according to Harvard’s Joint Center for Housing Studies, which means plenty of people don’t have the financial room to walk away from a bad offer even if a landlord won’t budge. Having leverage on paper and being able to use it are two different things when your budget is already tight.

    So how do you actually negotiate? Start by researching what similar units in your building or neighborhood are renting for right now, not what they rented for a year ago. Bring that number with you. Landlords expect prepared tenants to know the market, and vague requests rarely go anywhere.

    Person having a conversation with a landlord or property manager about lease terms

    Timing matters just as much as the number. Fall and winter tend to be slower rental seasons, which means less competition and more room for landlords to say yes. If your lease renewal falls during a slow season, that’s the moment to ask, not after signing for another year at the old terms.

    Think about: any extra room in your monthly budget matters more once you actually have it.
    Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed.

    Nationally, nearly 40% of rental listings now include some kind of concession, and Zillow estimates renters save $1,930 on average when they land a free month of rent.

    If a lower monthly rate isn’t on the table, ask about concessions instead. A free month, waived application or amenity fees, or a locked-in rate with no increase at renewal can all be worth more over a year than a small monthly discount. Landlords sometimes have more flexibility on these than on the sticker price itself.

    Nobody enjoys the awkwardness of asking a landlord for a better deal. That discomfort is real, and it’s usually smaller than the cost of staying quiet for another year.

    Metric20252026
    National vacancy rate7.2%8.6%
    National rent growth (YoY)1.5%0.4%
    U.S. average rent~$1,600$1,663

    The market shifted. Most renters haven’t caught up to that fact yet, and landlords aren’t going to be the ones to point it out.

    Have you ever tried negotiating your rent, and did it actually work?

    Disclaimer: This article is for general informational purposes only and does not constitute financial or legal advice. Rental markets and lease terms vary significantly by city and property. Consult a licensed real estate professional or tenant rights organization for guidance specific to your situation.
  • 92% of Americans Are Skipping Doctor Visits to Save Money — Here’s What That’s Actually Costing Them

    92% of Americans Are Skipping Doctor Visits to Save Money — Here’s What That’s Actually Costing Them

    A new survey found something that should worry more people than it does. Why are so many Americans delaying doctor visits to save money right now? According to a February 2026 analysis, 92% of US adults have delayed or avoided medical care because of cost.

    That’s not a typo. Nine out of ten adults, at some point, decided a doctor’s visit wasn’t worth what it might cost them.

    I’ve put off going to the doctor myself when something didn’t feel serious enough to justify the bill. That decision always feels small in the moment. It rarely feels small later.

    Person looking hesitant while holding a phone, considering whether to call a doctor

    According to research from healthcare marketplace Zocdoc, a doctor’s office visit for someone without insurance now averages $171 across major US cities. For a family living paycheck to paycheck, that number alone is enough to make people wait and see instead of booking an appointment.

    Young adults are getting hit hardest. Adults between 18 and 28 are the most likely group to delay or avoid care because of cost, and that pattern is showing up across nearly every income bracket, not just the uninsured.

    Young adult looking worried while reviewing a medical bill at home

    Read this: if healthcare costs are eating into your budget, it’s worth understanding what’s actually driving the numbers up in the first place.
    Your Health Insurance Bill Just Jumped 58%. Here’s What Actually Happened.

    The consequences aren’t staying small either. Direct polling from KFF found nearly one in five adults said their health actually got worse because they skipped a visit. For uninsured adults under 65, that share jumps to 42%, more than double the rate among those with coverage. Waiting on a checkup doesn’t just delay a bill, it sometimes turns a minor problem into a bigger, more expensive one later.

    Prescription costs are part of the same pattern. A separate KFF poll on prescription costs found 43% of insured adults have skipped or cut back on a prescribed medication due to cost, and that share climbs to 58% among adults without insurance. That’s not always a safe substitute, and it’s rarely something a pharmacist gets asked about before the switch happens.

    Person comparing over-the-counter medication options at a pharmacy shelf

    Not everyone reads this trend the same way. Some health economists argue that avoiding unnecessary care isn’t automatically bad, since a portion of routine visits in the US produce little medical value relative to their cost. The concern isn’t people skipping every appointment. It’s that cost, not medical judgment, is now the deciding factor for millions of people, even when something might actually be wrong.

    Think about: a bill you didn’t see coming can undo months of careful budgeting in a single visit.
    Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed.

    There are a few real options if cost is the thing standing between you and a visit. Community health centers often charge on a sliding scale based on income, sometimes far below the $171 average. Urgent care clinics post their prices upfront in a lot of states now, which makes comparing options possible before you walk in. And asking directly about a cash-pay discount, before the visit, sometimes gets you a lower rate than what shows up on the bill after insurance processes it.

    Waiting room inside a community health clinic offering income-based pricing

    Nobody decides to skip a doctor’s visit because they don’t care about their health. Most people are doing basic math with a number that doesn’t leave much room, and betting that today’s problem can wait until there’s more room in the budget.

    GroupDelayed or Avoided Care Due to Cost
    All US adults92%
    Adults 18–2894.2%
    Health got worse (uninsured, under 65)42%

    Skipping one visit rarely feels like a financial decision at the time. It usually just feels like waiting. The cost of that wait doesn’t show up until later, and by then it’s often bigger than the bill would’ve been.

    Have you ever put off seeing a doctor because of the cost, and did it end up costing you more later?

    Disclaimer: This article is for general informational purposes only and does not constitute medical or financial advice. Individual healthcare situations vary. Consult a licensed healthcare provider or financial advisor for guidance specific to your circumstances.

  • Why Your Electric Bill Keeps Going Up in 2026 (And What You Can Actually Do About It)

    Why Your Electric Bill Keeps Going Up in 2026 (And What You Can Actually Do About It)

    Why is my electric bill so high in 2026? If you’ve asked yourself that lately, you’re not imagining things, and it’s not just your usage. Electricity prices have jumped over 36% since 2020, and this year the increase is picking up speed again.

    Part of the reason has nothing to do with your home at all. AI data centers across the country are pulling massive amounts of power from the same shared grids that supply households, and the infrastructure needed to support them is expensive. Someone has to pay for that buildout, and in a lot of states, that someone is you.

    Person looking concerned while reviewing a high electricity bill at home

    Here’s how this actually plays out. Utilities are requesting record-high rate hikes right now, and some of that spending goes toward new power lines, substations, and grid capacity built specifically to handle data center demand. According to Goldman Sachs research on electricity pricing, households could see prices rise another 6% through 2027, on top of what’s already happened. That’s not a one-time bump. It’s a trend building year over year.

    This isn’t happening the same way everywhere. States with heavy data center construction, like Virginia, Ohio, and parts of the mid-Atlantic region, are seeing the sharpest increases, and a Fortune report on utility rate hikes found utilities requested a record $31 billion in rate increases in 2025 alone. Some states have started pushing back. New York put a moratorium on new large data center permits, and New Jersey passed rules aimed at protecting regular ratepayers from covering those infrastructure costs. If you live in a state without protections like that yet, your bill is more likely to reflect the buildout directly.

    Rows of server towers inside a modern data center facility consuming large amounts of power

    Read this: if utility costs are only one piece of a bigger squeeze on your monthly budget, it helps to see the full picture.
    Your Paycheck Isn’t Keeping Up With Inflation. Here’s Why.

    Not every expert agrees on how much of the blame belongs to AI. Some research, including a working paper from the Electric Power Research Institute covered by Fortune, found that data center activity actually helped lower retail electricity costs in earlier years by spreading fixed grid costs across more usage. The picture is more complicated than “AI caused this,” and multiple factors, including aging infrastructure and higher fuel costs, are part of the increase too. Still, the direction for most households right now points the same way: bills going up, not down.

    So what can you actually control? A few things make a real difference without requiring a lifestyle overhaul. Shifting heavy appliance use, like laundry and dishwashers, to off-peak hours can lower costs if your utility offers time-of-use pricing. Many providers list this option on their website, and it’s often something people never bother checking.

    Person adjusting a home thermostat to reduce energy use and lower their electric bill

    Think about: small changes to how you use energy stack up the same way small savings habits do everywhere else.
    Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed.

    A programmable thermostat is another one worth the upfront cost. Even a few degrees of adjustment while you’re asleep or away from home adds up over a full billing cycle. Some utility companies also offer rebates for upgrading to efficient appliances, and those rebates rarely get advertised well, so it’s worth calling and asking directly instead of waiting to see it in your inbox.

    Nobody enjoys opening a bill that’s higher than last month for reasons that have nothing to do with anything they did. That frustration is fair, and it doesn’t mean there’s nothing worth doing about it. Checking a rate plan or calling a utility company feels like a small step, but it beats staring at the same bill every month and hoping it goes back down on its own.

    If your state is considering new rules on how data center costs get distributed, public comment periods are sometimes open to residents, and a few states have already responded to public pressure with real policy changes. Keeping an eye on your state utility commission’s website is one way to know if that applies where you live.

    YearAvg. Residential Price (per kWh)Change
    202012.76 cents
    Feb 202617.44 cents+36.7%
    Projected Sept 202719.01 cents+9% more

    This isn’t a problem that disappears by ignoring the bill. It’s worth checking your rate plan, asking your utility about time-of-use pricing, and tracking whether your state is doing anything to shift costs away from households.

    Is your electric bill higher than it was a year ago, and have you found anything that’s actually helped bring it down?

    Disclaimer: This article is for general informational purposes only and does not constitute financial advice. Utility rates and regulations vary by state and provider. Consult your local utility company or a licensed financial advisor for guidance specific to your situation.
  • 48% of Americans Made a Real Money Comeback in 2026 — Here’s What They Actually Did

    48% of Americans Made a Real Money Comeback in 2026 — Here’s What They Actually Did

    Why are fewer Americans living paycheck to paycheck this year? A new survey just found something unusual: the share dropped from 69% to 48%, the biggest one-year drop the survey has ever recorded.

    That’s not a small shift. For years, that number only climbed. Now it’s falling fast, and most people haven’t even heard about it yet.

    Living paycheck to paycheck means having almost nothing left over after bills each month. One missed shift, one car repair, and the whole budget collapses. For over half of working Americans, that was daily reality just twelve months ago.

    Woman looking at a bank statement with a calmer, more relieved expression at her kitchen table

    So what actually changed? According to the Debt.com 2026 survey of over 1,000 Americans, the drop lines up with two things happening at once. Inflation cooled off from its recent highs, and more people started actively budgeting than ever before, with 53% now tracking a monthly budget compared to under half a few years ago.

    That second part matters more than people realize. A separate five-year study found that budgeting habits climbed steadily even as financial anxiety rose, which suggests people didn’t wait for the economy to fix itself. Many Americans changed their habits first, and the numbers followed.

    Not everyone is seeing the same improvement though. The drop was sharpest among people who already had some financial cushion to work with. Households already carrying heavy debt or supporting kids on a single income still report living paycheck to paycheck at far higher rates than the national average.

    Couple reviewing household spending and paperwork together at the kitchen table

    This is why the number matters even if your own situation hasn’t changed yet. A national average dropping doesn’t mean the pressure disappeared everywhere. It means enough people found breathing room that the overall trend shifted, while plenty of households are still stuck exactly where they were.

    Check this: if your income situation is part of what’s holding you back, credit isn’t always the reason people assume.
    Your Income Doesn’t Affect Your Credit Score. Here’s What Actually Does.

    There’s a counterargument worth taking seriously here. Some economists point out that wages still haven’t caught up with prices in every sector, and that a survey asking people how they feel about their finances can shift based on mood as much as actual numbers. A Bankrate survey from the same period found that most Americans still don’t have enough saved to cover three months of expenses, even with the paycheck-to-paycheck number improving. Feeling less stretched month to month and being financially secure are not the same thing.

    That gap is worth sitting with. Getting through the month without running out of money is progress. It’s not the same as having a real cushion for when something actually goes wrong. Nobody feels rich just because the bills got paid on time for once. That relief is real, but it fades fast the moment something unexpected shows up.

    Person setting up an automatic savings transfer using a banking app on their phone

    Same principle applies here as it did during the worst stretch of inflation. Small, automatic habits tend to outperform big one-time efforts. Setting even $20 a week to move automatically into savings does more over a year than waiting for a bonus or tax refund to catch up all at once.

    If the national trend is finally turning, the smartest move isn’t to relax. It’s to use whatever extra room shows up in the budget to build the safety net most people still don’t have.

    Learn this: the amount recommended for true financial safety hasn’t gone anywhere, even while the paycheck-to-paycheck number drops.
    Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed.

    YearLiving Paycheck to PaycheckHave a Monthly Budget
    2021Not tracked in this format47%
    202569%Not tracked in this format
    202648%53%

    The takeaway isn’t that the money problems are solved. It’s that real behavior change, tracked in real surveys, actually moves the needle over time. That’s rare good news in personal finance, and it deserves attention even if your own numbers haven’t caught up yet.

    Has your own month-to-month budget gotten any easier this year, or does it still feel the same as it did in 2025?

    Disclaimer: This article is for general informational purposes only and does not constitute financial advice. Individual financial situations vary. Consult a licensed financial advisor for guidance specific to your circumstances.

  • Why Most Americans Fail at Saving (And the One Habit That Changes Everything)

    Why Most Americans Fail at Saving (And the One Habit That Changes Everything)

    I used to be one of those people. I’d open my savings account, feel motivated, and tell myself this month would be different. I’d save $200. Maybe even $300. And for a week or two, I’d stick to it.

    The truth is I never actually failed because I was lazy. I failed because I kept trying to save using only willpower. And willpower is like a muscle that gets tired. Mine gave up every single month.

    Then I’d see something I wanted. A subscription service. A meal out. New clothes. And the savings account would sit untouched for the next three months.

    The cycle repeated for years. I wanted to save. I knew I should save. But I never actually saved consistently.

    According to recent research, I’m not alone. 38% of Americans say their biggest financial regret is not saving money. And 54% of Americans now live paycheck to paycheck, up from 42% just five years ago.

    Saving StatisticPercentageTimeframeContext
    Biggest Regret: Not Saving38%CurrentFinancial regret
    Living Paycheck to Paycheck54%2026Current rate
    Paycheck to Paycheck (5 yrs ago)42%2021Past rate
    Growth in Rate+12%5 yearsDeteriorating trend
    Confident in 2026 Goals45%Planning 2026If using right strategy

    Automatic Savings Example:

    Starting AmountTimeframeTotal Saved
    $25-50/month3 months$75-150
    $25-50/month12 months$300-600

    The statistics are clear: most people fail at saving. Not because they’re lazy or careless. They fail because they’re using the wrong method.

    Check this too: 37% of Americans Still Budget With Pen and Paper

    Why Traditional Saving Doesn’t Work

    When I decided to “get serious” about saving, I tried the textbook approach: Open a savings account. Set a goal. Manually transfer money each month.

    Sounds good in theory. In practice? It failed within weeks.

    Here’s why: every month, I had to make a conscious decision to transfer money. And every month, there was a good reason not to. The car needed repairs. The kids needed something. An unexpected expense came up.

    My willpower was the only thing protecting my savings. And willpower is exhaustible.

    Person sitting at desk looking worried, struggling with financial decisions

    The problem isn’t that people lack discipline. The problem is that manual saving requires willpower every single month. And most people’s willpower breaks before their savings goals are reached.

    The One Habit That Actually Works

    Everything changed for me when I discovered something obvious: stop relying on willpower.

    Once I automated it, saving became invisible. I didn’t have to be motivated. I didn’t have to make a choice. The money just moved. That’s when I finally stopped failing.

    Instead, I set up automatic transfers. Money moved from my checking account to savings the day after I got paid. I didn’t have to think about it. I didn’t have to make a choice. It just happened.

    The difference was dramatic. Suddenly, saving wasn’t about motivation anymore. It was just what happened with my money.

    Savings automation is poised to accelerate as more Americans use tools that automatically move money into savings and optimize cash flow without manual intervention. The data shows this works. When saving is automatic, people actually save.

    This is the one habit that changes everything: Remove yourself from the equation.

    Read this: Why I Used to Avoid Opening My Own Bank App

    Person successfully tracking finances and budget on computer

    Why 2026 Is Different

    In 2025, nearly half (45%) of Americans say they feel confident in their ability to reach their 2026 financial goals. That confidence is warranted — if they use the right strategy.

    The tools are better now. You can set up automatic transfers in minutes. You can get high-yield savings accounts that actually pay you decent interest. You can even automate investments.

    The technology makes it easier than ever to save without relying on willpower.

    The Counter-Argument: What If I Need The Money?

    The most common objection I hear: “But what if I need to access that money?”

    Here’s the honest answer: you’ll still access it if you absolutely need to. Emergency funds exist for a reason. But by making it slightly less convenient, you prevent the impulse withdrawals.

    When money requires one extra click to access, you’re less likely to tap it for a non-emergency. When it’s in a separate account entirely, even less likely.

    The friction is intentional. It protects your savings from yourself.

    Person confidently making a positive financial decision

    How to Actually Start

    You don’t need a complicated plan. You don’t need to save $500 a month. You just need to automate something.

    Start small. $50 a month. Even $25. Set it to move automatically the day after payday. Don’t think about it. Don’t adjust it. Just let it work.

    After three months, you’ll have $75-$150 without ever making a decision. After a year, that’s $300-$600 just from removing yourself from the process.

    Once you see this work, you’ll increase it. Because unlike manual saving, where one missed month kills your motivation, automatic saving builds momentum. You see the account grow. You feel it working. You get encouraged to do more.

    The Hard Truth About Saving

    The reason most people fail at saving isn’t a character flaw. It’s poor strategy.

    They’re trying to save using willpower. Willpower is finite. It fails.

    The people who actually save? They don’t rely on willpower. They automate. They set it and forget it. They remove the decision-making from the equation.

    In 2026, with so many Americans making financial resolutions, this is the one change that actually sticks.

    Stop trying harder. Start saving automatically.

    Your future self will thank you.

    So what’s stopping you from setting up an automatic transfer today?

    Worth knowing: 53% of Americans Can’t Cover a $1,000 Emergency

    Disclaimer: This article is for educational purposes only and should not be considered as financial or investment advice. Savings strategies, automation tools, and account types vary by bank and individual circumstances. Consult with a qualified financial advisor before opening new accounts or making major financial decisions.

  • Almost a Third of Americans Feel Financially Broke — Even When They’re Not. I Know the Feeling.

    Almost a Third of Americans Feel Financially Broke — Even When They’re Not. I Know the Feeling.

    person looking at smartphone with worried expression

    I remember the moment clearly.

    I had just checked my bank balance. There was money there. More than last month, actually. But I didn’t feel relieved. I felt the same knot in my stomach I always felt.

    That’s the trap with money dysmorphia — no amount of money fixes it because the problem isn’t the money. It’s the voice in your head that keeps saying it isn’t enough. You can’t budget your way out of a lie you believe about yourself.

    Why?

    Because my brain kept telling me: “It’s not enough. It’ll never be enough.”

    Turns out, I wasn’t alone.

    A recent study found that 29% of Americans suffer from “money dysmorphia” — a distorted view of their own finances that makes them feel poor even when they’re doing okay financially (Credit Karma’s Money Dysmorphia Report, 2026, based on a national survey of 1,039 U.S. adults conducted January 2026).

    For Gen Z, it’s even higher — 43%.

    Money Dysmorphia StatisticPercentageDemographicSourceYearSurvey Details
    Money Dysmorphia Rate29%General US AdultsCredit Karma20261,039 adults (Jan 2026)
    Money Dysmorphia Rate43%Gen ZCredit Karma2026Subset of 1,039
    Says It Hurts Finances95%People with money dysmorphiaCredit Karma2026Of the 29-43% affected
    stressed person looking at laptop

    What is money dysmorphia exactly?

    It’s when your financial reality doesn’t match your financial feelings.

    You might have a steady job. You might be saving something each month. But you still feel like you’re falling behind. You compare yourself to others online. You see people buying houses, going on vacations, and you wonder: “What’s wrong with me?”

    Connected: Why I Stopped Thinking About Money All the Time

    The study also found that 95% of people with money dysmorphia say it hurts their actual financial situation. They make worse decisions because they feel desperate, even when they’re not.

    I’ve been there.

    What I learned about my own money dysmorphia:

    When I felt “poor,” I made poor choices. I’d avoid checking my accounts. I’d spend small amounts to feel better. I’d say yes to things I couldn’t afford because I wanted to feel “normal.”

    The feeling was the problem. Not the number.

    Once I realized that, everything changed. I stopped trying to earn my way out of anxiety and started trying to think my way out of it. The numbers didn’t need to change — my brain did.

    calm person writing in a notebook

    Here’s what started helping me:

    1. Stop comparing. I unfollowed people who made me feel behind. Their highlight reel isn’t my reality.
    2. Check the actual numbers. I started looking at my accounts every morning — not to panic, but to know. The truth is usually less scary than what your brain imagines.
    3. Talk about it. The study found that people who openly discuss money with friends and family feel less anxious. I started doing this. It helped more than I expected.
    4. Separate feelings from facts. Just because I feel behind doesn’t mean I am behind. Feelings are real, but they’re not always true.

    This helps too: 60% of Americans Bought Secondhand Last Year

    The honest truth:

    Money dysmorphia isn’t about your bank balance. It’s about your brain lying to you.

    The fix isn’t getting more money. The fix is changing how you see the money you already have.

    Question for you: When was the last time you actually checked your numbers and compared them to how you feel about your money? Try it today. You might surprise yourself.

    Face the numbers: Why I Used to Avoid Opening My Own Bank App

    Disclaimer: This article is for educational purposes only and should not be considered as financial or mental health advice. Money dysmorphia and financial anxiety vary by individual and require personalized assessment. Consult with a qualified mental health professional or financial advisor if financial distress is significantly impacting your wellbeing.

  • Why I Stopped Thinking About Money All the Time (And What I Did Instead)

    Why I Stopped Thinking About Money All the Time (And What I Did Instead)

    stressed person looking at calculator and bills on desk

    I used to think about money all day. Every single day. From the moment I woke up until I went to sleep.

    The worst part wasn’t the stress itself — it was thinking I had to feel that way. Like worrying constantly somehow meant I was being responsible. Nobody told me you could be smart about money AND stop torturing yourself about it.

    Do I have enough for this month?

    What if something unexpected happens?

    How will I pay this bill?

    This constant thinking was exhausting me. Not just my mind, but my body too. I felt tired even when I hadn’t done anything.

    A recent survey found that 73% of adults say money is a major source of stress in their lives (APA’s Stress in America survey, 2023, national sample of 3,500 adults). That’s huge. Three out of every four people feel the same way I did.

    Money Stress StatisticPercentageSourceYearSample Size
    Money = Major Stress Source73%APA Stress in America20233,500 adults
    Approximate Population~3 in 4Equivalent ratio2023General

    But I realized something important: Thinking about a problem isn’t the same as solving it.

    Same method: 37% of Americans Still Budget With Pen and Paper

    calm person writing in a notebook with a pen

    So I started doing something different.

    1. I set a specific time to think about money

    Instead of worrying all day, I set aside 15 minutes every morning. Just 15 minutes. I sit down, look at my numbers, and plan. After that, I stop. I don’t think about money again until the next day.

    Is it easy? No. But it works.

    1. I turned my worry into action

    Worry says: “What if I don’t have enough?”

    Action says: “What can I do today to make things better?”

    Instead of worrying about money, I started looking for work. Any work. Even small steps forward reduce anxiety more than just thinking about moving forward.

    Living this: Is Your Side Hustle Working, or Are You Just Tired?

    1. I remembered that money is a tool, not the goal

    We work to live. We don’t live to work.

    Money should serve your life, not the other way around.

     happy family sitting together at dinner table

    When I focus on my family, my kids, my health — money becomes just a means. Not the only thing that matters.

    This sounds simple, but it took me years to actually believe it. That my kids would remember the time I spent with them, not the spreadsheet I was staring at. Once I accepted that, the money stress didn’t disappear, but it lost its grip on everything.

    The bottom line:

    You can’t control everything about your financial life. But you can control how you think about it.

    If you’re stressed about money all the time, try this: set a specific time to worry about it, then stop. Turn your anxiety into small daily actions. And remember — you’re more than just numbers in a bank account.

    Question for you now: What’s one small thing you can do today, even if it’s tiny, to ease your money stress? Let me know in the comments.

    Next step: Why I Used to Avoid Opening My Own Bank App

    Disclaimer: This article is for educational purposes only and should not be considered as mental health or financial advice. Money anxiety and stress management strategies vary by individual. Consult with a qualified mental health professional or financial advisor if financial stress is significantly impacting your wellbeing.