Tag: 2026-trends

  • 401(k) Balances Just Hit a Record High — So Did Emergency Withdrawals From Them

    401(k) Balances Just Hit a Record High — So Did Emergency Withdrawals From Them

    Something strange happened with American retirement accounts in 2025. Balances hit an all-time high. So did the number of people raiding those same accounts just to survive.

    Vanguard’s newest report found the average 401(k) balance climbed to $167,970 by the end of 2025, a record. At the same time, 6% of plan participants took a hardship withdrawal that same year, also a record, and triple the rate from before the pandemic.

    Those two numbers shouldn’t move together. One says people are saving more than ever. The other says a growing share of them can’t make it through a crisis without pulling from that same account.
    Person looking stressed while reviewing a retirement account balance statement

    Here’s what’s driving the gap. According to Yahoo Finance’s coverage of Vanguard’s How America Saves report, layoffs surged to their highest level since the pandemic in 2025, and credit card delinquencies hit a 13-year high. Rising retirement balances came mostly from strong stock market gains and automatic enrollment features, not from people having more spare cash to set aside. The savings and the desperation grew from two completely different sources.

    Most hardship withdrawals aren’t going toward anything optional. The IRS recognizes six approved reasons for a hardship withdrawal, and the top ones are medical bills, preventing eviction or foreclosure, and funeral costs. This isn’t a luxury purchase problem. It’s people using retirement money as a last resort because nothing else was left.
     Eviction or foreclosure notice paperwork laid out on a table

    Worth knowing: an emergency fund exists specifically to prevent this exact situation from happening to your retirement money.
    Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed.

    The real cost of a hardship withdrawal isn’t just the tax bill, though that part hurts too. A TheStreet analysis of the Vanguard data found that a 35-year-old who pulls out $10,000 today loses more than $76,000 in future growth by retirement age, assuming a standard 7% annual return. A 45-year-old taking a $20,000 withdrawal loses roughly $77,400 in potential growth over the shorter remaining timeline. Unlike a 401(k) loan, a hardship withdrawal can never be paid back into the account.

    Not every financial planner sees this trend as purely alarming. Some point out that the same report shows record numbers of employees enrolled in retirement plans, and stronger long-term investing behavior overall, with only 5% of participants making trades even during market volatility. The system is working as designed for a lot of people. It’s the growing minority pulling out early that’s the concerning half of the story.
    Financial advisor discussing retirement options with a client at a desk

    Think about: the earlier you build a real safety net outside your retirement account, the less likely you are to ever need to touch it early.
    You’re Allowed to Save an Extra $7,500 for Retirement. Most People Don’t.

    If you’re facing a real emergency and a hardship withdrawal feels like the only option, a few alternatives are worth checking first. A 401(k) loan lets you pay yourself back over time instead of losing the money permanently, though it comes with its own risks if you leave your job before repaying it. Some employers also offer emergency savings features built directly into the retirement plan now, specifically designed to prevent people from needing to touch their long-term savings at all.

    Nobody takes money out of their own retirement account because they want to. It’s usually the last option left standing after everything else has already been tried.

    Metric202020242025
    Hardship withdrawal rate2%5%6% (record)
    Average 401(k) balanceLowerRising$167,970 (record)
    Cost to a 35-year-old on $10K withdrawal~$76,000 in lost growth

    A record balance and a record withdrawal rate happening in the same year isn’t a contradiction. It’s a picture of an economy where some people are getting ahead, and others are barely holding on, using the same accounts to do both.

    Have you ever had to consider pulling money from a retirement account early, and what did you end up doing instead?

    Disclaimer: This article is for general informational purposes only and does not constitute financial or tax advice. Retirement account rules and tax consequences vary by individual circumstances. Consult a licensed financial advisor or tax professional for guidance specific to your situation.
  • How to Use Record-High Apartment Vacancies to Negotiate Your Rent Down in 2026

    How to Use Record-High Apartment Vacancies to Negotiate Your Rent Down in 2026

    Why does everyone assume rent only goes up? That assumption made sense for years. It doesn’t anymore, at least not everywhere, and most renters have no idea the numbers just shifted in their favor.

    Apartment vacancies hit a record 8.6% in early 2026, up from 7.2% just months earlier. That means landlords have more empty units sitting unrented than they’ve had in years, and empty units cost landlords money every single day they stay empty.

    I remember signing a lease years ago without asking a single question about the price, because it never occurred to me that the number on the page wasn’t final. Looking back, that assumption cost me more than it should have.

    Person reviewing a lease agreement while considering negotiating the rent price

    Here’s why this matters for you directly. When vacancy rates climb this high, according to CoStar Group’s 2026 Multifamily National Report, property managers often extend more concessions just to fill units. That includes waived fees, a free month of rent, or flexibility on the monthly price itself, especially in buildings that have sat vacant for weeks.

    This isn’t happening everywhere the same way. National rent growth slowed to just 0.4% year over year, way down from 1.5% the year before, but the picture changes city by city. Places like Chicago, Cincinnati, and Philadelphia are still seeing real increases, while other markets are flat or even falling. Checking your specific city’s vacancy trend, not just the national headline, tells you how much leverage you actually have.

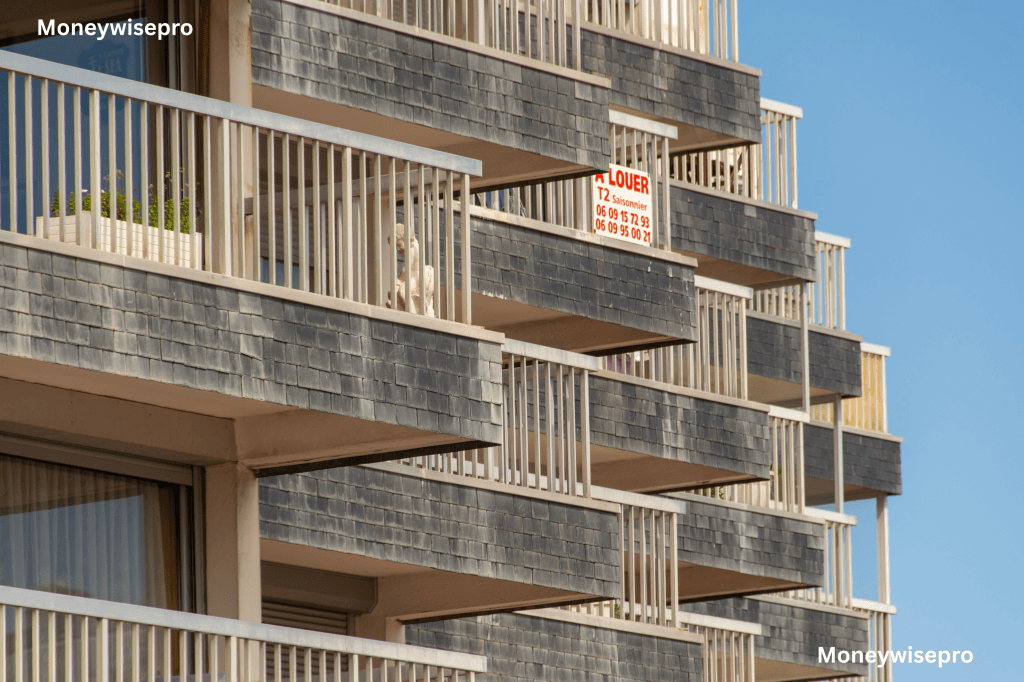
    Apartment building with a for rent sign, showing an empty unit available

    Worth knowing: rent isn’t the only monthly cost quietly climbing while your paycheck stays flat.
    Your Paycheck Isn’t Keeping Up With Inflation. Here’s Why.

    Not everyone agrees renters have real power right now. Some housing economists point out that the number of renters facing serious cost burdens just hit a record high too, according to Harvard’s Joint Center for Housing Studies, which means plenty of people don’t have the financial room to walk away from a bad offer even if a landlord won’t budge. Having leverage on paper and being able to use it are two different things when your budget is already tight.

    So how do you actually negotiate? Start by researching what similar units in your building or neighborhood are renting for right now, not what they rented for a year ago. Bring that number with you. Landlords expect prepared tenants to know the market, and vague requests rarely go anywhere.

    Person having a conversation with a landlord or property manager about lease terms

    Timing matters just as much as the number. Fall and winter tend to be slower rental seasons, which means less competition and more room for landlords to say yes. If your lease renewal falls during a slow season, that’s the moment to ask, not after signing for another year at the old terms.

    Think about: any extra room in your monthly budget matters more once you actually have it.
    Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed.

    Nationally, nearly 40% of rental listings now include some kind of concession, and Zillow estimates renters save $1,930 on average when they land a free month of rent.

    If a lower monthly rate isn’t on the table, ask about concessions instead. A free month, waived application or amenity fees, or a locked-in rate with no increase at renewal can all be worth more over a year than a small monthly discount. Landlords sometimes have more flexibility on these than on the sticker price itself.

    Nobody enjoys the awkwardness of asking a landlord for a better deal. That discomfort is real, and it’s usually smaller than the cost of staying quiet for another year.

    Metric20252026
    National vacancy rate7.2%8.6%
    National rent growth (YoY)1.5%0.4%
    U.S. average rent~$1,600$1,663

    The market shifted. Most renters haven’t caught up to that fact yet, and landlords aren’t going to be the ones to point it out.

    Have you ever tried negotiating your rent, and did it actually work?

    Disclaimer: This article is for general informational purposes only and does not constitute financial or legal advice. Rental markets and lease terms vary significantly by city and property. Consult a licensed real estate professional or tenant rights organization for guidance specific to your situation.
  • Why Your Electric Bill Keeps Going Up in 2026 (And What You Can Actually Do About It)

    Why Your Electric Bill Keeps Going Up in 2026 (And What You Can Actually Do About It)

    Why is my electric bill so high in 2026? If you’ve asked yourself that lately, you’re not imagining things, and it’s not just your usage. Electricity prices have jumped over 36% since 2020, and this year the increase is picking up speed again.

    Part of the reason has nothing to do with your home at all. AI data centers across the country are pulling massive amounts of power from the same shared grids that supply households, and the infrastructure needed to support them is expensive. Someone has to pay for that buildout, and in a lot of states, that someone is you.

    Person looking concerned while reviewing a high electricity bill at home

    Here’s how this actually plays out. Utilities are requesting record-high rate hikes right now, and some of that spending goes toward new power lines, substations, and grid capacity built specifically to handle data center demand. According to Goldman Sachs research on electricity pricing, households could see prices rise another 6% through 2027, on top of what’s already happened. That’s not a one-time bump. It’s a trend building year over year.

    This isn’t happening the same way everywhere. States with heavy data center construction, like Virginia, Ohio, and parts of the mid-Atlantic region, are seeing the sharpest increases, and a Fortune report on utility rate hikes found utilities requested a record $31 billion in rate increases in 2025 alone. Some states have started pushing back. New York put a moratorium on new large data center permits, and New Jersey passed rules aimed at protecting regular ratepayers from covering those infrastructure costs. If you live in a state without protections like that yet, your bill is more likely to reflect the buildout directly.

    Rows of server towers inside a modern data center facility consuming large amounts of power

    Read this: if utility costs are only one piece of a bigger squeeze on your monthly budget, it helps to see the full picture.
    Your Paycheck Isn’t Keeping Up With Inflation. Here’s Why.

    Not every expert agrees on how much of the blame belongs to AI. Some research, including a working paper from the Electric Power Research Institute covered by Fortune, found that data center activity actually helped lower retail electricity costs in earlier years by spreading fixed grid costs across more usage. The picture is more complicated than “AI caused this,” and multiple factors, including aging infrastructure and higher fuel costs, are part of the increase too. Still, the direction for most households right now points the same way: bills going up, not down.

    So what can you actually control? A few things make a real difference without requiring a lifestyle overhaul. Shifting heavy appliance use, like laundry and dishwashers, to off-peak hours can lower costs if your utility offers time-of-use pricing. Many providers list this option on their website, and it’s often something people never bother checking.

    Person adjusting a home thermostat to reduce energy use and lower their electric bill

    Think about: small changes to how you use energy stack up the same way small savings habits do everywhere else.
    Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed.

    A programmable thermostat is another one worth the upfront cost. Even a few degrees of adjustment while you’re asleep or away from home adds up over a full billing cycle. Some utility companies also offer rebates for upgrading to efficient appliances, and those rebates rarely get advertised well, so it’s worth calling and asking directly instead of waiting to see it in your inbox.

    Nobody enjoys opening a bill that’s higher than last month for reasons that have nothing to do with anything they did. That frustration is fair, and it doesn’t mean there’s nothing worth doing about it. Checking a rate plan or calling a utility company feels like a small step, but it beats staring at the same bill every month and hoping it goes back down on its own.

    If your state is considering new rules on how data center costs get distributed, public comment periods are sometimes open to residents, and a few states have already responded to public pressure with real policy changes. Keeping an eye on your state utility commission’s website is one way to know if that applies where you live.

    YearAvg. Residential Price (per kWh)Change
    202012.76 cents
    Feb 202617.44 cents+36.7%
    Projected Sept 202719.01 cents+9% more

    This isn’t a problem that disappears by ignoring the bill. It’s worth checking your rate plan, asking your utility about time-of-use pricing, and tracking whether your state is doing anything to shift costs away from households.

    Is your electric bill higher than it was a year ago, and have you found anything that’s actually helped bring it down?

    Disclaimer: This article is for general informational purposes only and does not constitute financial advice. Utility rates and regulations vary by state and provider. Consult your local utility company or a licensed financial advisor for guidance specific to your situation.