Tag: saving-money-tips

  • Why Did Your HOA Fee Jump the Moment You Closed on the House?

    Why Did Your HOA Fee Jump the Moment You Closed on the House?

    You signed the closing disclosure, budgeted around the exact HOA fee it listed, and felt good about the number. Then the first real statement showed up higher, and it kept climbing every few months after that. If your HOA fee jumped right after closing, you are not imagining it, and you are far from alone in 2026.

    Homeowners associations are not a niche detail anymore. Nearly 43.6% of U.S. homes listed for sale in 2025 carried an HOA, up from 41.9% in 2024 and just 34.3% back in 2019, according to a Realtor.com analysis distributed through PR Newswire. New construction leans even further into this pattern. About 84% of newly built U.S. homes sold in 2022 came with an HOA already attached, according to Associa, one of the largest HOA management companies in the country.

    The real issue is not that HOAs exist. It is that the fee written on a closing disclosure is a snapshot of one moment, not a promise about what comes next. Many Americans discover that gap only after they have already signed, when a routine board meeting quietly raises dues or drops a special assessment notice into the mailbox a few months later.
    Close-up of a hand signing an offer to purchase real estate document with a black pen

    The national number alone tells part of the story. The median HOA fee climbed to $135 a month in 2025, up 8% from $125 in 2024, per that same Realtor.com report. Two forces are driving most of the increase. Climate-related insurance costs have pushed premiums higher across entire regions, and legislative changes following the 2021 Surfside condo collapse have added real pressure on associations to build up reserves and run more frequent structural inspections. Miami-Fort Lauderdale shows what that looks like at the extreme end, with a median HOA fee of $617 a month, which works out to 26.9% of a typical mortgage payment in that metro alone.

    Florida is where the newer 2026 pressure is sharpest. House Bill 913 pushed the deadline for completing Structural Integrity Reserve Studies to December 31, 2025, and buildings that were coasting on underfunded reserves for years are now catching up all at once. Special assessments in older coastal buildings have ranged from $10,000 to more than $100,000 per unit, and reporting from SavingAdvice.com found some owners watching their total monthly housing cost double in under two years. Miami-Dade County now offers assistance loans up to $50,000 with 40-year repayment terms for households under 140% of the area median income, which is a real sign of how serious the gap has gotten for regular families, not just for outlier cases.

    Cost Component20242025/2026What Changed
    Median monthly HOA fee (national)$125$135Up 8% year over year
    Homes for sale with an HOA41.9%43.6%Continuing a multi-year climb from 34.3% in 2019
    Miami-Fort Lauderdale median HOA fee$617/monthEqual to 26.9% of a typical mortgage payment
    Florida special assessment range (older coastal buildings)$10,000-$100,000+ per unitDriven by HB 913’s SIRS deadline of Dec 31, 2025

    Florida also tightened separate Milestone Inspection deadlines to December 31, 2024 or 2025 depending on a building’s age, for any condo 30 years or older, and new transparency rules now require associations with 25 or more units to post budgets and reserve studies online within 30 days of completion. That last rule matters more than it sounds. A buyer who knows where to look can now check an association’s real financial health before ever calling the seller’s agent, instead of relying on whatever gets mentioned during a showing.

    Check this:
    Falling Behind on Your Mortgage in 2026 Just Got a Lot Less Forgiving

    A $50 jump on a monthly statement does not sound like much until it shows up three times in one year with no warning attached. That kind of surprise has a way of making an otherwise solid home purchase feel a lot less secure than it did on closing day.
    Modern apartment building exterior showing multiple rows of balconies against a clear sky

    There is a real document that exists specifically to catch this before it becomes a surprise, and most first-time buyers never ask for it by name. It is called an HOA resale certificate, sometimes labeled a closing statement or estoppel letter, and associations are generally required to produce one within five to fifteen business days of a request. According to Associa, it discloses the current dues amount and payment frequency, any outstanding fees or violations tied to the seller, pending litigation involving the association, current reserve fund balances, and any expenditures the board already has planned. A buyer who requests and actually reads this document before closing gets a real preview of where fees are headed, instead of finding out from the next mailed statement.

    None of this is a reason to avoid HOAs altogether. A low HOA fee at signing is not automatically good news. It can just as easily mean an association that has been underfunding its reserves for years, which is exactly the setup that leads to the six-figure special assessments now hitting parts of Florida. A well-run association with a fully funded reserve, a real master insurance policy, and predictable maintenance on the roof, elevators, and shared amenities can genuinely protect a home’s value better than no HOA at all.

    Worth knowing:
    Security Deposit Alternatives Sound Free. They’re Not, and Here’s the Real Math
    Close-up of a hand holding cash bills while pressing keys on a calculator

    None of this means walking away from every home that has an HOA attached. It means treating the number on the closing disclosure as a starting point, not a ceiling. Before signing anything, request the resale certificate directly and read the reserve fund section specifically, not just the dues total. Ask the seller’s agent or the HOA management company whether any special assessment has been discussed or voted on in the last two years, even informally, and ask directly whether the building has completed its required structural or reserve study on time. A board that answers that question quickly and clearly is usually a better sign than a low current fee ever could be. And when budgeting for the new home, add a real cushion above the listed HOA fee rather than treating it as a fixed cost, the same way a smart budget already leaves room above a mortgage estimate for property tax and insurance changes.

    This helps:
    Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed

    An HOA fee is just one more recurring bill sitting alongside a mortgage, property tax, and homeowners insurance, and it is easy to lose track of which one actually went up. A free payment tracker built for exactly this kind of recurring cost can make the real monthly total easier to see before it quietly climbs again.

    Have you ever checked an HOA’s resale certificate before signing, or did the real monthly cost only show up after you had already moved in?

    Disclaimer: MoneyWisePro is not a real estate professional or financial advisor. This article is for general information only and is not real estate or financial advice. Confirm current HOA fees, reserve status, and any planned assessments directly with the association or a licensed real estate professional before making decisions based on this article.
  • Why Rent-to-Own Furniture Never Has to Show You an Interest Rate

    Why Rent-to-Own Furniture Never Has to Show You an Interest Rate

    A $300 television can end up costing $832 through a rent-to-own furniture and electronics store. Run the math on that and the real interest rate lands around 254 percent, according to a Congressional Research Service report on these contracts. No lender could legally call that a loan without a giant warning label attached. Rent-to-own furniture gets to skip that label completely, and the reason is a legal technicality almost nobody explains.

    Millions of Americans use rent-to-own stores every year because approval takes minutes and a bad credit history almost never matters. No bank statement, no credit score pulled, no denial letter in the mail. Big names like Rent-A-Center, Aaron’s, and store-checkout partners like Progressive Leasing and Katapult all run on the same basic model: pay weekly, own the item once the full schedule is paid. For someone furnishing an apartment on a tight paycheck, a $25 weekly payment on a couch feels manageable in a way a $900 lump sum never will. That appeal is real, and it explains why the industry keeps signing up new customers even as prices climb.

    Worth knowing:
    Your Cash Advance App Interest Rate Is Higher Than the Tip Makes It Look

    That appeal is about to get more expensive to act on. Tariffs pushed manufacturers’ input costs up roughly 3 percent for appliances and about 2.5 percent for furniture between March and December of 2025, according to research from the Chicago Federal Reserve. Those higher manufacturing costs tend to work their way to the price tag over time, not overnight. When the retail cash price of a couch or a refrigerator climbs, the total cost of a rent-to-own furniture lease on that same item climbs right along with it, since the weekly payment is built as a multiple of that cash price, not a fixed number set once and left alone.

    Young mother reading a rental agreement on laptop at a kitchen table with a toddler nearby

    Here’s the part almost nobody explains clearly. A rent-to-own agreement is legally written as a short-term lease a customer can cancel anytime, not as a loan. Federal Reserve Regulation Z, the rule that enforces the Truth in Lending Act, specifically excludes leases a consumer can walk away from without penalty. Walk into that same store and finance a purchase with a store credit card instead, and federal law forces the retailer to print the APR directly on the paperwork. Sign a rent-to-own lease on the exact same couch, and there’s no APR requirement at all, because on paper the customer is renting, not borrowing. Consumer advocates have argued for years that these contracts should be regulated as credit sales instead of leases, precisely because the end result looks identical to a loan. The industry has resisted that classification just as consistently, since a lease label is what keeps the APR disclosure off the page.

    The Congressional Research Service report that documented the $832 television described a broader pattern, not one unusual case. Across the industry, the total of rent-to-own payments regularly runs two to three times the retail price of an item, sometimes more. A handful of states have pushed back directly. New York law caps total rent-to-own payments at 2.25 times an item’s cash price, according to the New York City Bar Association’s consumer law guidance. Most states have no cap of any kind, which means an $832 television is legal nearly everywhere in the country right now.

    Man using a laptop calculator beside unopened moving boxes in an empty living room

    Rent-to-own isn’t pure predation, and that’s worth saying plainly. Walking away from a lease mid-contract, without owing the remaining balance, is a real legal right a traditional loan doesn’t give anyone. If a job falls through three months into a lease, handing back the recliner ends the obligation completely. Some larger rent-to-own companies now report on-time payments to consumer reporting agencies too, which can help build a payment history for someone who’s never had one before. Those are genuine trade-offs, not marketing spin.

    Think about:
    I Almost Fell Into the Buy Now Pay Later Trap, Here Is What Stopped Me

    The trade-off only makes sense once the real total cost gets written down, not guessed at. Before signing anything, ask the store for the cash price of the exact item in writing, then multiply the weekly payment by the number of weeks in the contract. Compare those two numbers side by side before deciding anything. A rent-to-own furniture store legally has to give a shopper the cash price on request, even though nothing requires it to print an APR next to it.

    Close-up of two people

    A secured credit card or a small credit-builder loan from a local credit union usually costs far less over the same stretch of time, and both exist specifically for people without an established credit history. A short layaway plan, where a store holds the item until it’s fully paid off before handing it over, is another option worth asking about directly. Local buy-nothing groups and secondhand marketplaces are worth a quick look too, since a gently used version of the same couch or dresser often costs less than a single month of rent-to-own payments. None of these move as fast as walking out of a store with a couch the same afternoon. That speed is exactly what the higher price is paying for.

    Since a rent-to-own payment is just one more weekly or biweekly bill sitting alongside everything else, a free payment tracker built for exactly this kind of recurring cost can make the real total easier to see before it quietly adds up.

    This helps:
    53% of Americans Can’t Cover a $1,000 Emergency, I’m Building Mine From Zero, Here’s My Plan

    Needing a place to sit or a working refrigerator right now is not a character flaw. The real math on rent-to-own furniture just deserves to be seen clearly before a signature makes it permanent.

    What Gets DisclosedStore Credit CardRent-to-Own Lease
    APR legally required on paperworkYesNo
    Credit check typically requiredYesAlmost never
    Real example (per CRS report)APR printed on the contract$300 TV totaling $832, about 254% effective
    Can you walk away without owing the restNoYes

    Have you ever added up what a rent-to-own payment plan actually costs compared to paying cash over time?

    Disclaimer: MoneyWisePro is not a financial advisor. This article is for general information only and is not financial or legal advice. Contact a financial advisor or a consumer law attorney for guidance on your specific situation.

  • Why Did My Car Registration Fee Go Up This Year?

    Why Did My Car Registration Fee Go Up This Year?

    You open the renewal notice expecting the same number you paid last year, and instead the total is twenty, thirty, sometimes fifty dollars higher. If your car registration fee went up this year and you have no idea why, you are not imagining it, and there is no mistake on your bill. Across the United States in 2026, a wave of states are raising these fees on purpose, and most drivers never see it coming until the renewal lands in their mailbox.

    Driver looking surprised while opening a car registration renewal bill at home

    Most drivers assume registration is one flat number the state sets once and never touches again. In reality it is usually a stack of separate charges layered together: a base state fee, a weight-based fee tied to how heavy your vehicle is, sometimes a value-based tax tied to what the car is worth, a county or local add-on, and in a growing number of states, a separate electric or hybrid vehicle surcharge. Each piece can move on its own schedule, set by a different part of the state government, which is exactly why the total on your renewal can jump even in a year when nothing about your own car has changed.

    This matters because most people only find out their car registration fee went up when the bill is already sitting in front of them, with no breakdown of which piece actually moved. A weight fee, a road fund add-on, and a flat base charge can all live on the same renewal notice, and states rarely explain the split in plain language. Knowing the pieces exist is the difference between assuming your state made a mistake and understanding exactly which line item changed and why.

    New Mexico is a clear example of the 2026 wave. Passenger vehicle registration fees there jumped roughly 25 percent, moving from a range of about 21 to 56 dollars a year up to roughly 26 to 70 dollars, effective July 1, 2026, according to the state’s own transportation department. The reasoning New Mexico gave is blunt: the fee had not moved since 2004, inflation has climbed more than 75 percent since then, and the state needs an estimated 70 million dollars a year for the State Road Fund because more than half of its roads need repair.

    Ohio moved on a similar timeline. Starting January 1, 2026, the standard non-commercial registration fee rose from 11 to 16 dollars, a 45 percent increase reported by WCPO, with the extra money going directly to the Ohio State Highway Patrol, which had been running on registration-fee funding frozen for more than twenty years while its real buying power quietly shrank.

    Maryland’s increase came in stages instead of one jump. A typical passenger car registration went from about 87 dollars a year before 2024 to 110.50 dollars in July 2024, then up again to 120.50 dollars by July 2025, an increase of roughly 38 percent across two rounds, according to Maryland’s own published fee numbers. Heavier passenger vehicles were hit even harder, climbing from around 93.50 dollars a year to 191.50 dollars, more than double.

    Related read: why your car insurance renewal went up even with a clean driving record, which is the same kind of quiet annual squeeze on a different bill.

    Calculator, car keys, and a rising cost chart representing higher annual vehicle fees

    The other piece of the 2026 story is electric and hybrid vehicles. Since EVs and plug-in hybrids do not buy gasoline, they contribute nothing to the fuel taxes that traditionally pay for road repair, so states have been adding a separate yearly surcharge to make up the difference. By 2025, 39 states already had some version of this fee, ranging from roughly 50 to 290 dollars a year, and the list keeps growing every legislative session.

    StateOld Annual FeeNew Fee (2026)Increase
    New Mexico$21–$56$26–$70~25%
    Ohio (non-commercial)$11$16~45%
    Maryland (standard passenger car)$87 (pre-2024)$120.50 (2025)~38%

    Many Americans open that renewal notice expecting the exact same number as last year, and feeling blindsided by a higher total is a completely normal reaction, not something to feel foolish about. Once you know these fees are stacked from several separate pieces that each move on their own timeline, the jump stops feeling random and starts feeling like something you can actually plan for.

    If you want to know your own state’s real number before the next renewal notice shows up, check your state’s Department of Motor Vehicles website directly instead of guessing from a national average, because these fees are set state by state and sometimes county by county. Search your own state’s DMV site for its vehicle registration fee schedule and look at the actual dollar table, not someone else’s blog estimate, so you are not caught off guard the next time your car registration fee goes up.

    It is also worth checking whether your own state is one of the ones still debating a fee increase for next year rather than one that already passed it, since most of these bills get discussed months before they take effect. A quick search for your state’s name plus the phrase vehicle registration fee bill through your state legislature’s own website will usually show you if something is already moving through committee. Catching it early gives you time to budget for the higher number instead of being surprised by it at renewal time, and it also means you are reading real proposed numbers instead of a rumor someone shared online.

    Electric vehicle plugged into a home charger, tied to new state EV registration surcharges

    Related read: why the average car payment just hit a record high if rising loan costs are also squeezing your budget this year.

    Registration is just one of several yearly car costs that are easy to forget about until the bill shows up, alongside insurance renewals, inspection fees, and now these registration hikes, all landing at different times of the year. If you want a simple way to see these costs coming instead of getting surprised every time, grab the no-cost annual expense planner here and plug in your own renewal dates.

    Did your own registration renewal go up this year, and did you know the real reason before reading this?

    Disclaimer: MoneyWisePro is not a financial advisor. This article is for general information only and is not financial advice. Contact a licensed financial professional for guidance on your specific situation.

  • Does Splitting Your Rent Payment Into Two Actually Save You Money?

    Does Splitting Your Rent Payment Into Two Actually Save You Money?

    Rent is due on the first of the month. Paychecks do not care what the calendar says. That mismatch is now big business. A wave of new apps in 2026 lets you try splitting your rent payment into two smaller chunks instead of paying it all at once, and millions of renters are already signing up, according to Fortune’s reporting on the trend.

    The pitch sounds simple. Instead of handing over your full rent on day one, an app like Flex breaks it into two payments spread across the month, so your rent lines up closer to when your paycheck actually lands. Public radio’s Marketplace reported that housing costs have gotten so tight for so many households that this kind of flexibility now feels less like a luxury and more like survival.

    Here is the part that gets skipped in most of the coverage: splitting your rent payment is not free. Someone is charging for that flexibility, and the real math on what it costs over a full year is bigger than the small monthly number makes it look.

    Young woman in a gray sweater checking a rent payment app on her phone at a small kitchen table

    Take Flex, one of the biggest names in this space. Its own rent payment page lists a $5.99 monthly membership fee, a 0.5% processing fee on the total rent amount, and a split fee of up to 3% that does not shrink even if you pay everything back early. Paying with a credit card instead of a bank account adds another 2.5% on top. On a $1,800 rent payment, the split fee alone can run close to $54 in a single month, before the membership fee is even added in.

    Do that every month for a year and the fees stop looking small. A renter paying $1,800 a month who uses the full split option every single month could be paying somewhere between $130 and $200 a year just for the option of breaking one payment into two. That is real money that never touches the actual rent, the security deposit, or anything that improves the apartment.

    Rent Payment MethodExtra Monthly CostReports to Credit Bureaus?
    Paying full rent yourself, on time$0Rarely, unless your landlord reports manually
    Landlord agrees to a split due date directly$0 (if they agree)Rarely, unless your landlord reports manually
    Rent-split app, paid from a bank accountRoughly $5.99 + 0.5% + up to 3%Yes, on-time payments only
    Rent-split app, paid with a credit cardSame as above, plus 2.5%Yes, on-time payments only
    Paying 5+ days late, landlord late feeOften 5%-10% of rent, by state and leaseNo

    Check this:
    Security deposit alternatives sound free too, and they are not either

    There is one genuine upside worth being fair about. Flex states it reports on-time payments to all three major credit bureaus, and the company says it will never report anything except an on-time payment. For someone with a thin credit file, or someone rebuilding credit after a rough stretch, turning your biggest monthly bill into a payment history that actually counts toward your score is a real benefit that a landlord accepting a paper check never gives you.

    Man in a blue collared shirt reviewing a rising credit score graph on his laptop at home

    But building credit and covering a shortfall are two different problems, and splitting your rent payment only genuinely helps with the first one. CFPB research on buy now pay later use already flagged the bigger risk here: when people stack several small installment plans across different bills, the payments quietly pile up in the background until one missed paycheck knocks the whole thing over. Rent is usually the single largest bill in a household budget. Turning it into an installment plan on top of a phone bill, a BNPL plan for groceries, or a DoorDash order bought on credit is exactly the kind of stacking that research points to.

    This is why an app like this makes the most sense for a narrow group of people, not everyone. Freelancers and gig workers whose income arrives in lump sums rather than steady biweekly paychecks can genuinely benefit from choosing their own payment dates. Someone whose paycheck lands on the 3rd but whose rent is due on the 1st has a two-day gap that a split payment can bridge without ever missing a due date. For those specific situations, the fee can be a fair price for avoiding a landlord’s own late fee, which frequently runs higher than anything Flex or a similar app charges.

    Couple sitting on a couch comparing a wall calendar against a stack of household bills together

    Nobody signs up for one of these apps because they enjoy paying a fee. They sign up because the due date feels impossible and the fee feels smaller than the alternative in that exact moment.

    For everyone else, the math usually points the other way. If the real reason for wanting to split a rent payment is that the money simply is not there yet, an app fee on top of the rent does not fix that gap, it just moves it two weeks down the calendar while adding a cost to get there. Many renters are safer building even a small buffer, even $50 or $100 sitting untouched, than adding a recurring fee to their biggest bill every single month.

    Learn this:
    BNPL looked smart for a DoorDash order too, until the credit score questions started

    Before signing up for anything, it is worth pricing out splitting your rent payment the same way this article just did: add up the membership fee, the processing fee, and the split fee for a full year, then compare that number to what your own landlord actually charges for a late payment or a payment plan, if they offer one at all. Some landlords will agree to a split payment with zero fee if you simply ask, especially if you have paid on time for a while already.

    If you are already splitting rent alongside a Buy Now Pay Later plan or two, keeping every due date straight gets messy fast. A free BNPL Payment Tracker can help you line them all up before one of them sneaks past you.

    Same principle applies:
    Hidden hotel fees finally have to show up before you book, rent fees do not have that protection yet

    Many renters using these apps right now are reacting to a due date that feels impossible to hit, not doing the yearly math before they sign up. Rent has grown faster than paychecks in most US cities for years now, and any tool that promises breathing room is going to look appealing in the moment, even when the real cost only shows up later.

    So before you split your next rent payment into two, have you actually compared what the app charges against what your landlord would charge, or would even agree to for free?

    Disclaimer: MoneyWisePro is not a financial advisor. This article is for general information only and is not financial advice. Check your own lease terms and talk to your landlord or a licensed financial advisor before signing up for any rent payment app based on this article.
  • Why Your Hotel’s Resort Fee Might Finally Show Up Before You Book in 2026

    You find a hotel room for $129 a night. Great price, you think.

    Then you check in. The final bill says $164.

    That extra $35 is a resort fee. It was sitting in the fine print the whole time, waiting for the one moment you couldn’t easily back out.

    Millions of Americans know this exact feeling. A federal rule now in effect is supposed to change it. Since 2025, more hotels have to show the real price, resort fee included, before you ever hit book. Here is what is actually happening, and what it means for your next trip.

    What a Resort Fee Really Is

    A resort fee is a mandatory daily charge added on top of your room rate. Hotels call it different things. Destination fee. Amenity fee. Facility fee. The name changes. The math does not.

    You get charged whether you use the pool, the gym, or the WiFi it supposedly covers. Skip all three, and you still pay the resort fee.

    These charges are not small pocket change. According to travel research from Upgraded Points, resort fees typically run from under $10 a night to more than $50 a night, and at some high-end properties, like Dorado Beach in Puerto Rico, the daily fee tops $100. Even a well-known spot like the Algonquin Hotel in New York City adds a $30-a-day destination fee.

    Stack that over a five-night trip, and a cheap-looking room stops being cheap at all.

    Las Vegas is the clearest example of this. The average resort fee on the Strip runs $45 to $51 a night, and top-tier properties charge even more. That is exactly why a $59 room on a booking app can turn into more than $100 a night once you actually check in. This has been standard practice there for over a decade, long before any federal rule tried to catch up with it.

    Elegant hotel lobby with front desk where guests check in

    The New Rule Changes the Timing, Not the Fee

    Here is the part a lot of travelers get wrong. The FTC’s rule on unfair or deceptive fees, which took effect on May 12, 2025, does not ban resort fees. It never promised to.

    What it actually does is force hotels and event-ticket sellers to show the full price, mandatory fees included, the first time a price appears on screen. Not at checkout. Not after you have already mentally committed to the trip.

    So the resort fee itself is still completely legal. What changed is where it shows up. It now has to appear early, in plain numbers, instead of hiding until you are already checked in.

    State regulators have not slowed down either. Attorneys general in multiple states are still actively enforcing pricing-transparency cases against hotels and ticket sellers well into 2026, which is exactly why this rule still matters months after it first took effect.

    A Quick Look at What Resort Fees Actually Cost

    Hotel TypeTypical Daily Resort FeeAdded Cost Over 5 Nights
    Budget or Midscale Hotel$10 to $25$50 to $125
    Major Resort or Casino Hotel$25 to $45$125 to $225
    Luxury Resort$45 to $100+$225 to $500+
    Hand holding a smartphone open to a hotel booking app screen

    Why This Still Catches People Off Guard

    Even with the rule in place, plenty of travelers still get surprised. Some booking sites operating outside US jurisdiction move slower to comply. Some hotels list the resort fee upfront, but bury it in small gray text under a bigger, bolder room price. Technically legal. Still easy to miss when you are booking on your phone at 11 p.m.

    That is the real lesson here. The law gives you the right to see the number. It does not force you to actually read it.

    That first hotel bill shock is a specific kind of annoying, the fine-print kind, not the something-actually-went-wrong kind. Once you know to check the total price first, that particular annoyance mostly disappears for good.

    How to Actually Protect Yourself When You Book

    Look at the total price, not the nightly rate, before you enter any payment information. Most booking sites now show an estimated total that includes the resort fee if you scroll past the big headline number.

    Call the hotel directly and ask one plain question: what is my total nightly cost, including all mandatory fees? Getting a straight answer before you book is still the simplest way to avoid a surprise at checkout, no matter how you end up reserving the room.

    Some stores hide their own version of a surprise charge at checkout too, and the habit of double-checking the final number before you commit is worth carrying into every purchase, not just hotel bookings.

    Read this next: Why Do So Many Stores Charge You to Return Something Now?

    Check whether the property calls it a resort fee, amenity fee, or destination fee. The label changes. Your total cost math should not.

    Third-party booking apps are usually where this fee hides the longest, since some of them still show only the room rate on the search results page and add the resort fee one screen later. Booking directly through the hotel’s own website often shows the full price sooner, right at the point you pick a room type.

    Guest handing a credit card to a hotel receptionist at checkout

    If you already got charged a resort fee that was never disclosed clearly before you booked, you have real options. Contact the hotel first and ask for it to be waived or refunded, citing the FTC disclosure rule directly. Travel advocates also say it is worth escalating to a complaint with your state attorney general, or a dispute with your credit card company, if the hotel will not budge. Neither route guarantees a refund, but both have worked for other travelers who tried.

    Hidden costs also love to show up in pairs outside of travel.

    Worth a look before your next lease: Security Deposit Alternatives Sound Free. They’re Not, and Here’s the Real Math.

    A resort fee is not going away in 2026. What is changing is your ability to see it coming, if you know to look for it before you type in your card number.

    Have you ever gotten to the front desk and found a bigger bill waiting for you than you expected?

    Disclaimer: This article is for general information only and is not financial or legal advice. Fee rules, hotel policies, and enforcement can change, so always confirm the total price directly with the hotel or booking platform before you pay.

  • Your 401(k) Catch-Up Contribution Rule Just Changed for 2026 — Here’s Who It Hits

    One in five Americans over 50 has nothing saved for retirement, according to AARP’s 2026 Financial Security Trends Survey. If you are in the other four, and you have been counting on catch-up contributions to close the gap, a new catch-up contribution rule kicking in this year changes how that extra money gets taxed, and a lot of people are going to find out the hard way.

    For years, anyone 50 or older could put extra money into a 401(k) on top of the regular limit, and choose whether that extra money went in pre-tax or as Roth. That choice is gone for a large group of workers starting in 2026.

    Starting this year, if your wages from your employer topped $150,000 in 2025, every dollar of your catch-up contribution has to go into a Roth account. Not traditional, pre-tax money. Roth only. That means the immediate tax deduction you used to count on when you maxed out your catch-up is gone, and you pay income tax on that money now instead of later.

    Senior couple reviewing retirement paperwork together on their living room couch

    The IRS put real numbers on this. For 2026, the standard catch-up contribution for anyone 50 and older is $8,000, on top of the regular $24,500 deferral limit. If you turn 60, 61, 62, or 63 this year, you get a bigger super catch-up window instead, $11,250, part of the SECURE 2.0 changes that were finalized this year.

    Here is the part that catches people off guard. The income test looks backward, not forward. It checks what your employer paid you in 2025, not what you are earning right now. So even if your income drops in 2026, or you switch to a lower-paying job, you are still locked into this catch-up contribution rule for the whole year if last year’s number crossed the line.

    And if your employer’s 401(k) plan does not offer a Roth option yet, the rule does not quietly let you keep the pre-tax catch-up instead. Under the current guidance, you cannot make any catch-up contribution at all until your plan adds one. That is real savings capacity you lose, not just a change in how the money gets taxed. Some large employers have already rolled out a Roth option specifically to avoid this exact problem for their higher-paid staff.

    This catch-up contribution rule was not supposed to land this late. It was written into the SECURE 2.0 Act back in 2022 and was originally set to start in 2024. Payroll providers and plan administrators pushed back hard, saying they needed more time to rebuild how catch-up money gets routed and taxed inside their systems. The IRS granted transition relief twice, which is the only reason most higher earners are only running into this now, two years after the law first passed.

    One thing this rule does not touch: Traditional and Roth IRAs outside of a workplace plan. For 2026, the IRA contribution limit is $7,500, plus a separate $1,100 catch-up for anyone 50 and older, and that catch-up can still go in pre-tax if you use a Traditional IRA. It is a smaller number than a 401(k) catch-up, but it is one place higher earners can still choose pre-tax treatment on their own, without asking their employer for anything.

    Close-up of hands marking up a retirement contribution worksheet with a highlighter

    Check this:
    Your Emergency Fund Isn’t What It Used to Be

    None of this makes Roth a bad deal. It is a different deal. Money that goes in as Roth grows tax-free, and comes out tax-free in retirement, with no required minimum distributions forcing you to pull it out on the IRS’s schedule. If you expect to be in a lower tax bracket right now than you will be later, or you just want fewer tax surprises after you retire, paying the tax on catch-up money today is not the disaster this catch-up contribution rule first sounds like.

    The bigger problem is not Roth versus pre-tax. It is timing, and that part has not changed. A dollar put into catch-up contributions at 55 has roughly a decade to compound before a typical retirement age. Put in $32,500 a year for ten years at a 7% return, and you land close to $480,000 by 65. Wait until 62 to get serious about it, and three years of the same effort lands closer to $112,000, an amount that gets eaten fast by real living costs.

    Financial advisor showing a retirement contribution form to an older couple

    Read this:
    You’re Allowed to Save an Extra $7,500 for Retirement

    If you are anywhere near that $150,000 mark, or you are 50-plus and have not looked at your 2026 catch-up contribution setup yet, this is worth five minutes with your HR or benefits portal before your next paycheck goes out. Confirm whether your plan actually has a Roth option. Confirm what your 2025 W-2 wages were with that specific employer, since the threshold is per-employer, not your total household income. That is the difference between a contribution that goes in the way you expect, and one that quietly gets taxed in a way you never agreed to.

    Retirement paperwork has a way of getting ignored until the day it actually costs someone money. Nobody mails a warning letter before a quiet rule change like this one kicks in.

    Age Group2026 Total Contribution LimitCatch-Up PortionRoth-Only If 2025 Wages Exceeded $150,000?
    Under 50$24,500$0 (no catch-up available)Not applicable
    50 to 59$32,500$8,000Yes
    60 to 63$35,750$11,250Yes

    So have you actually checked whether your 2025 W-2 wages put you on the Roth side of this new catch-up contribution rule?

    Disclaimer: MoneyWisePro is not a financial advisor. This article is for general information only and is not financial advice. Contact a licensed financial advisor for guidance on your own retirement contributions and tax situation.

  • The Tip Screen Guilt Is Real, and It’s Quietly Draining Your Budget in 2026

    You hand over your card at the coffee counter, the self-checkout kiosk, or the tire shop, and the screen flips around asking for 18, 20, or 25 percent, with a cashier or camera lens somewhere nearby. That moment of tip screen guilt is not just in your head. Americans reluctantly tipped an average of 283 dollars in 2025 just from feeling pressured in that exact moment, money that never made it into a real budget plan.

    Digital tip prompts used to show up mostly at sit-down restaurants. Now they pop up at drive-throughs, hair salons, dog groomers, and self-checkout lanes where there is no server bringing you a plate at all. The screen does not care whether a human actually did extra work for you. It just asks, and most people feel too watched to hit the no tip button.

    That is the real problem behind tip screen guilt: it turns a voluntary reward into a rushed, emotional decision made under someone’s gaze, and that rushed decision quietly eats into money that was supposed to go somewhere else. Many Americans report changing how they shop and pay specifically because of this pressure, not because they suddenly decided service workers deserved more.

    Part of the trick is how the screen is designed in the first place. Most kiosks show a default set of options like 18, 20, and 25 percent instead of a blank field, and that starting point quietly shifts what feels normal to tip. Pick a low number and you feel like you are being cheap in front of the person watching the screen. Pick the highest number and you barely notice the extra few dollars sliding out of your account, one tap at a time, all month long.

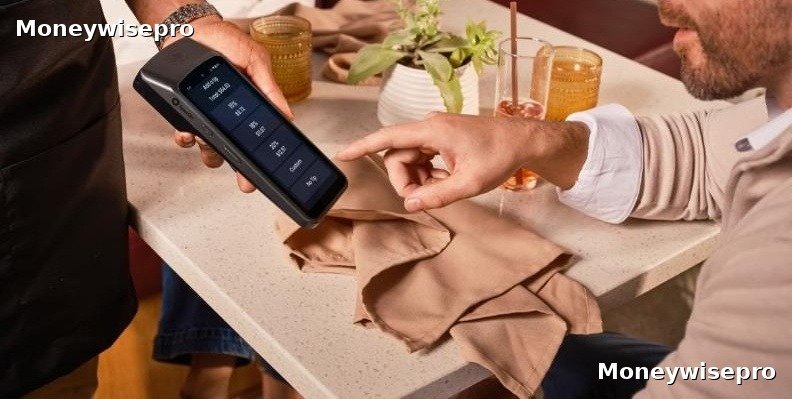
    Customer tapping a tip percentage option on a coffee shop point of sale screen

    The pressure is measurable, not just a feeling. A LendingTree survey found 66 percent of Americans feel pressured to tip once a screen puts the option in front of them, and 60 percent say they are tipping more now purely because the technology makes it easier to nudge them. Break that pressure down and it comes from three different directions: 27 percent said the pressure was self-imposed, 24 percent said they felt obliged by people standing nearby, and 19 percent said the pressure came directly from the person serving them. None of that is about generosity. It is about not wanting to look cheap in front of a stranger.

    The generational split is worth knowing if you are trying to budget realistically. Gen Z reports tipping more under this pressure at 73 percent, millennials at 72 percent, and parents with kids under 18 tip more often than people without kids, 72 percent versus 58 percent. Tip screen guilt hits hardest on people already juggling tight family budgets, not people with money to spare.

    Here is where it actually shows up in real dollars. The average person who gives in to tip screen guilt does it about 4.2 times a month and reluctantly adds around 24 dollars a month they did not plan to spend, according to Talker Research’s 2025 data reported by Fox Business. Add that up over a year and it lands close to that 283 dollar figure, money quietly leaking out of a grocery budget or an emergency fund one tap at a time.

    This helps: The Average American Wastes $205 a Year on Subscriptions They Don’t Even Use

    Handheld payment screen showing preset tip percentage buttons at a restaurant table

    There is a real counter-argument here, and it deserves honesty, not a blanket no-tip rule. Workers in genuinely tipped jobs in the United States, servers, bartenders, delivery drivers, often depend on tips to reach a livable wage because their base pay is legally allowed to be lower. Skipping a tip for someone who actually served your table is a different decision than skipping one at a self-checkout kiosk where no human did anything beyond programming the screen.

    That distinction is exactly why 2026 is turning into a pushback year instead of just another year of rising tip pressure. A WalletHub-based survey covered by TheStreet found close to 40 percent of Americans now believe tipping culture has gone too far and would support pulling it back, and Fox Business reported Americans are actively fighting the guilt-tipping trend for the first time, with total guilt-tip spending actually falling 38 percent from 2024 to 2025. People are starting to draw their own line instead of letting the screen draw it for them.

    The places where this pressure shows up the most are also the places with the least actual justification for a tip. Coffee counters where you order at a register and wait for your own name to be called, self-checkout lanes where you scanned every item yourself, and drive-throughs where nobody carried anything to a table are exactly where the screen still asks for 20 percent by default. A tip in those settings is not paying for labor you received, it is paying for the discomfort of saying no while someone is standing three feet away.

    Customer using a self-checkout kiosk screen with a printed receipt

    The fix is not becoming someone who never tips. It is deciding your rule before you are standing at the counter with the screen glowing in your face and someone watching. Decide ahead of time that table service, haircuts, and delivery drivers get a real tip, and that a machine you walked up to and scanned your own groceries on does not owe anyone a percentage just because it asked.

    Here is a quick look at how the guilt-tipping trend actually moved between 2024 and 2025, based on the LendingTree and Talker Research surveys cited above.

    Metric20242025
    Average annual guilt-tip spendingover $450$283
    Guilt tips given per month6.3 times4.2 times
    Extra amount tipped per monthhigheraround $24
    Americans who increased tipping that yearmajority trend uponly 11%

    That hesitation right before tapping a tip amount is a genuinely uncomfortable few seconds for most people, not a sign of being cheap. Once you realize the number on that screen has nothing to do with how good the service actually was, it gets a lot easier to just tap the honest amount and move on.

    Worth knowing: The Average American Spends $3,045 a Year on Impulse Buys

    Do you tip differently now than you did two years ago, or has the screen just quietly changed your habits without you noticing?

    Disclaimer: MoneyWisePro is not a financial advisor. This article is for general information only and is not financial advice. Contact a licensed financial advisor for guidance on your own household budget and spending decisions.

  • Why Did My Pet Insurance Premium Go Up With No Claims in 2026?

    Why Did My Pet Insurance Premium Go Up With No Claims in 2026?

    Your pet insurance renewal notice arrives and the new price makes no sense. You never filed a claim this year. Your dog had one routine checkup and nothing else. Yet somehow your premium jumped by 30 percent. If you are asking why your pet insurance premium went up with no claims in 2026, you are not imagining things, and you are far from alone.

    Something is shifting across the entire pet care industry right now. A nationwide survey from the American Veterinary Medical Association found that 81 percent of veterinarians reported noticeably more price-sensitive clients in 2025, up from 72 percent the year before. At the same time, actual clinic visits dropped roughly 3 percent, continuing a four-year slide. Many Americans are skipping the vet, not because their pets need less care, but because they can no longer afford as much of it. Pet care spending in the United States is projected to reach 165 billion dollars in 2026 alone, and insurance premiums are simply riding that same wave upward.

    Pet insurance premiums are climbing even faster than the vet bills behind them. Industry-wide increases are running 25 to 40 percent in 2026 alone. One widely cited example: a Trupanion policyholder’s premium rose from 128 dollars a month in 2024 to 251 dollars a month in 2026, a jump to just over 3,000 dollars a year for the exact same coverage. Some MetLife customers reported 50 dollar monthly jumps at renewal. And here is the part that catches people off guard, one documented case showed a 40 percent renewal increase with zero claims filed all year.

    Only 4.27 percent of pets in the United States currently carry any insurance policy at all, according to industry data from the North American Pet Health Insurance Association. That means roughly 95 percent of the 95 million pet-owning households in the country are paying every vet bill in cash, on a credit card, or not at all. For the small share who do carry a policy, a sudden 25 to 40 percent premium jump can feel like the insurance itself became the expensive part of owning a pet.

    A worried pet owner reviews a pet insurance renewal statement while calculating rising monthly costs

    So why does a pet insurance premium go up with no claims anywhere on the account? Three things are happening at once. Veterinary medicine has gotten far more advanced, and far more expensive. MRI scans, oncology treatment, and orthopedic surgery are now standard options at many clinics, and none of that barely existed in general practice fifteen years ago. Millions of pets adopted during the pandemic years are now entering the age bracket where health problems become common, and insurers underpriced that risk when they wrote those original policies. About 23 million American households, close to one in five, acquired a dog or cat during the pandemic, according to the ASPCA, and most of those pets are still in their homes today, aging into the years when vet visits get more frequent and more expensive. Insurers are also correcting their own math across the board. Claim frequency caught up with older pricing models, so premiums are being repriced industry-wide, whether or not one specific pet has ever filed a claim.

    ProviderWhat ChangedReported Increase
    TrupanionMonthly premium, same coverage$128/mo (2024) to $251/mo (2026), about 96% higher
    MetLifeRenewal jumpAbout $50 more per month
    SpotIncrease right after filing a claim25% jump within weeks
    Industry-wideGeneral 2026 trend25% to 40% higher premiums
    A veterinarian examines a dog on an exam table during a routine wellness checkup visit

    The price gap between clinics tells the same story from a different angle. One Missouri pet owner was quoted 2,600 dollars for her dog’s bladder stone surgery. After calling around, she found the identical procedure for 710 dollars at a rural clinic two hours away. Overall veterinary costs rose about 7.5 percent between 2024 and 2025 alone, and prices are up roughly 60 percent over the past decade.

    Nobody plans for a $2,600 vet bill on a random Tuesday. Money set aside for something else just disappears in one phone call.

    Worth knowing: 53% of Americans Can’t Cover a $1,000 Emergency. I’m Building Mine From Zero. Here’s My Plan

    Vet bills do not wait for a convenient month, and neither do the insurance renewals that follow them.

    This helps: Your Emergency Fund Isn’t What It Used to Be. Here’s What Changed

    If a pet insurance premium goes up with no claims and the new bill is hard to absorb, there are real options before reaching for a credit card or a payment app.

    A pet owner budgets at home with a laptop while their dog rests calmly nearby

    See also: I Almost Fell Into the Buy Now, Pay Later Trap. Here’s What Stopped Me

    Start by calling the provider and asking directly what changed. Some insurers will adjust the deductible or reimbursement percentage to bring the monthly cost back down, even if the base rate has increased. Second, get quotes from two or three vets before agreeing to any procedure over 500 dollars, since prices for the same surgery can vary by thousands of dollars depending on the clinic. Third, compare the current insurance premium against a basic wellness plan plus a self-funded emergency account, since for some pets and some budgets, insurance no longer makes financial sense once the premium climbs this high. Fourth, if a renewal jump feels disconnected from a pet’s actual health, ask the insurer directly whether the increase is tied to zip code, breed, or a region-wide rate filing, since many of these adjustments are approved state by state and have nothing to do with an individual claims history.

    None of this means pet insurance is a bad idea for every owner. For a young, healthy pet with years of coverage ahead, the math can still work out. The real problem is that most owners never see the renewal increase coming, and the letter explaining it rarely gives more than a vague line about rates changing in the area. A policy that made sense three years ago is worth checking again this year, line by line, before the next renewal notice quietly shows up in the inbox.

    Have you checked your own pet insurance renewal against what you were quoted last year, or does the new number only show up once you are already locked into the payment?

    Disclaimer: MoneyWisePro is not a licensed insurance agent or veterinarian. This article is for general information only and is not professional advice. Contact your own insurance provider or veterinarian for guidance about your specific pet and policy.